
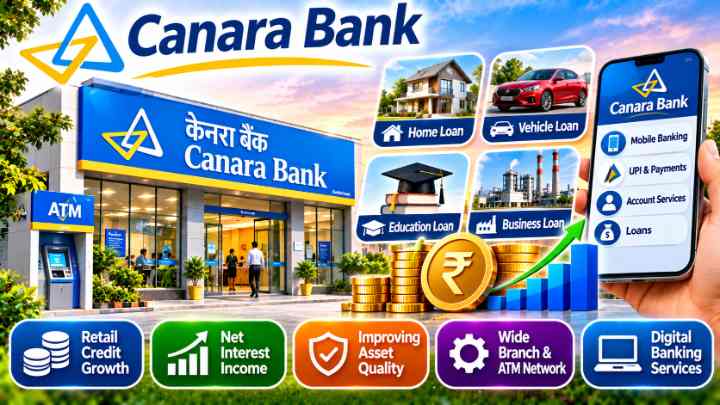
Explore Canara Bank's lending business, Q2 FY27 results, retail credit growth, asset quality, ECL provisioning and key risks.
- Canara Bank is a large public sector bank with a wide branch and ATM network across India and some international locations.
- Canara Bank serves customers through its branch and ATM network, offering deposit and lending services.
- Retail lending is an important growth area for Canara Bank.
What Canara Bank Does
Canara Bank is a large public sector bank with a wide branch and ATM network across India and some international locations. It provides banking services to retail customers and businesses, with lending and deposit-taking forming the foundation of its operations.
The bank’s business model revolves around accepting deposits and deploying those funds as loans. Its lending activity spans different customer segments, including retail borrowers. Retail credit has been an important area of expansion, growing 31.6% year on year.
Canara Bank also earns income beyond its core lending operations through fees and treasury activities. These sources contribute to its overall income, although net interest income remains a central measure of its banking performance.
Also Read: Vedanta: How Commodity Prices, Higher Volumes and Debt Reduction Drive Its Business
Customers and How Canara Bank Makes Money
Canara Bank serves customers through its branch and ATM network, offering deposit and lending services. Its customer base includes retail borrowers and other banking customers across the markets in which it operates.
The bank earns primarily through net interest income, commonly called NII. In simple terms, it is the difference between the interest a bank receives on loans and the interest it pays to depositors.
For example, when a bank accepts deposits and lends those funds to borrowers, it earns interest from its lending activities while paying interest on deposits. The difference contributes to net interest income. The bank’s ability to manage this spread is important for maintaining profitability.
Fee income provides another source of revenue. Banks earn fees from the services they provide, while treasury income contributes through their treasury operations. These activities are reported within non-interest income.

Retail lending is an important part of Canara Bank’s business expansion. Growth in retail credit can increase its lending base, but the quality of those loans also matters. A bank needs to balance credit growth with the ability of borrowers to repay.
This makes net interest income, non-interest income, asset quality and provisioning important measures when evaluating Canara Bank. Strong loan growth alone does not guarantee higher profits if funding costs, credit losses or operating expenses increase.
Growth Drivers
Retail lending is an important growth area for Canara Bank. The 31.6% year-on-year expansion in retail credit indicates strong growth in this part of its loan portfolio. Sustaining lending growth while maintaining repayment quality will be important for the bank.
Also Read: Shree Cement: How Premium Products, Sales Growth and Cost Management Drive Its Business
Improving asset quality also supports the bank’s financial performance. Lower gross and net NPA ratios reduce the proportion of loans classified as stressed, while the provision coverage ratio indicates the extent of provisions held against identified problem assets.
The bank’s wide domestic branch and ATM network, together with its international presence, forms the distribution base for its banking activities. Its ability to generate business through this network will remain relevant to its growth.
Competition and Risks
Margin pressure is another risk. Net interest income has grown strongly, but the bank’s ability to sustain that performance depends on the relationship between lending yields and deposit costs. A weaker margin could reduce the benefit of loan growth.
As a public sector bank, Canara Bank is exposed to the broader cyclicality of banking activity. Changes in credit conditions can affect loan growth, repayment behaviour and profitability. Credit cost normalisation is another consideration, particularly if provisioning requirements increase.
Also Read: REC: How Power and Infrastructure Financing Drive Its Business
The higher cost-to-income ratio also highlights the importance of controlling operating expenses. If costs rise faster than income, profitability can come under pressure even when the bank continues to grow its lending business.
What Investors Should Watch
Investors should first monitor net interest income and global net interest margin. These measures will help determine whether the bank can sustain the improvement in earnings generated by its lending operations. Performance against management’s FY27 margin guidance will be particularly relevant.
The expected ECL provisioning requirement is another priority. Investors should follow the timing and scale of these provisions and assess how they affect reported profit over the coming years.
Also Read: Punjab National Bank: How Deposits, Lending and Improving Asset Quality Drive Its Business
Non-interest income and the cost-to-income ratio are also important. The decline in non-interest income and the increase in the half-year cost-to-income ratio show that profitability depends on more than loan growth alone.
Finally, investors should track retail credit growth and the overall expansion of advances alongside the bank’s credit quality. Strong lending growth is valuable only when it is supported by disciplined credit performance and sustainable margins.
Conclusion
The main issue for investors is the expected ECL provisioning requirement and its potential effect on future profitability. Net interest margins, credit quality, operating costs and provisioning trends will be important indicators when assessing whether Canara Bank can sustain its earnings growth.
Also Read: PFC: How Power Sector Financing and Renewable Energy Loans Drive Its Business
Financial Disclaimer: This article is for educational and informational purposes only. It is not investment advice or a recommendation to buy or sell Canara Bank shares. Investors should conduct independent research before making financial decisions.
Keep learning with OneTrader
Explore structured lessons and practical guides to build your market knowledge.

Need a laugh after all that money talk?
Paisa LOL: India's funniest finance page, with memes, comics, jokes and long funny stories.
