
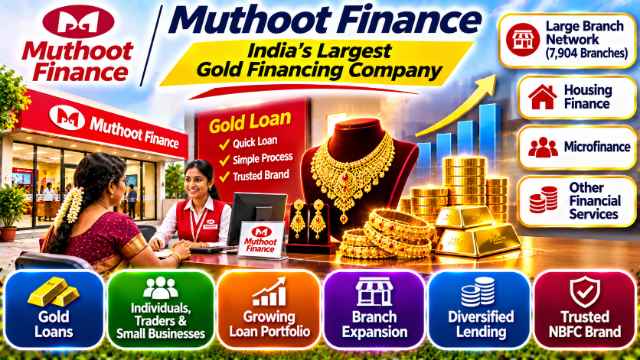
Explore Muthoot Finance's gold loan business, Q2 FY27 results, record loan assets, rising gold prices, growth opportunities and key risks.
- Gold prices are an important influence on Muthoot Finance’s business.
- Gold price volatility is a key risk.
- Muthoot Finance has built its business around lending against household gold jewellery, supported by a large branch network and additional financial services businesses.
What Muthoot Finance Does
Muthoot Finance is India’s largest gold financing company by loan portfolio. Its core business is lending money against household gold jewellery, serving customers who need credit by pledging gold as security.
The company operates through a large branch network, with the Muthoot Finance group having 7,904 branches as of 30 September 2026. Alongside its core gold loan business, the group has subsidiaries in housing finance, microfinance and other financial services.
Gold financing is central to the company’s business model. Its lending activity is supported by the value of gold pledged by borrowers and the interest earned on loans.
Customers and How Muthoot Finance Makes Money
Muthoot Finance primarily serves individuals, small traders and small businesses that need access to credit. Customers pledge household gold jewellery to obtain loans rather than selling their gold.
Also Read: Vedanta: How Commodity Prices, Higher Volumes and Debt Reduction Drive Its Business
The company earns interest on the money it lends against gold. The amount of lending activity depends on customer demand, the value of pledged gold and the company’s ability to grow its loan portfolio.
Its subsidiaries in housing finance, microfinance and other financial services provide additional lending activities beyond gold-backed loans. This diversification broadens the group’s presence across different customer financing needs.

Growth Drivers
Gold prices are an important influence on Muthoot Finance’s business. Higher gold prices can increase the value of jewellery pledged by customers and support lending activity. Rising demand for gold loans provides another source of growth.
Branch expansion can help the company reach more borrowers and increase access to its lending services. Its extensive branch network is central to serving customers across different locations.
Diversification into housing finance, microfinance and other lending activities provides additional growth opportunities beyond the core gold loan portfolio. The company’s ability to expand these businesses while maintaining lending quality will be important to its longer-term performance.
Competition and Risks
Gold price volatility is a key risk. A decline in gold prices can reduce the value of pledged collateral and increase the risks associated with loan recovery and gold auctions.
Asset quality also requires attention. The sequential rise in standalone gross NPAs makes it important to monitor overdue loans, recoveries and the company’s ability to maintain lending discipline as its portfolio expands.
Regulatory changes by the Reserve Bank of India concerning gold loans could affect lending practices and business operations. Competition from banks and other NBFCs is another challenge, particularly in attracting borrowers and maintaining loan growth.
If gold prices fall, the company may also face greater auction and recovery risks when borrowers fail to repay their loans.
Also Read: Siemens Energy India: How Power Transmission, Generation and Project Backlogs Drive Its Business
What Investors Should Watch
Investors should track growth in gold loan assets under management and the company’s progress against its revised FY27 growth guidance. Gold prices and customer demand will remain important influences on the size of its lending portfolio.
Asset quality deserves equal attention. The movement in gross NPAs, loan recoveries and auction-related risks will help investors assess whether rapid portfolio growth is being achieved without a deterioration in lending quality.
The contribution from housing finance, microfinance and other lending businesses is also worth monitoring. Regulatory developments and competition from banks and NBFCs will influence the company’s ability to sustain growth and profitability.
Conclusion
Muthoot Finance has built its business around lending against household gold jewellery, supported by a large branch network and additional financial services businesses. Rising gold prices and demand for gold-backed credit have supported strong growth in its loan portfolio and earnings.
Also Read: Shree Cement: How Premium Products, Sales Growth and Cost Management Drive Its Business
Financial Disclaimer: This article is for educational and informational purposes only. It is not investment advice or a recommendation to buy or sell Muthoot Finance shares. Investors should conduct independent research before making financial decisions.
Keep learning with OneTrader
Explore structured lessons and practical guides to build your market knowledge.

Need a laugh after all that money talk?
Paisa LOL: India's funniest finance page, with memes, comics, jokes and long funny stories.
