
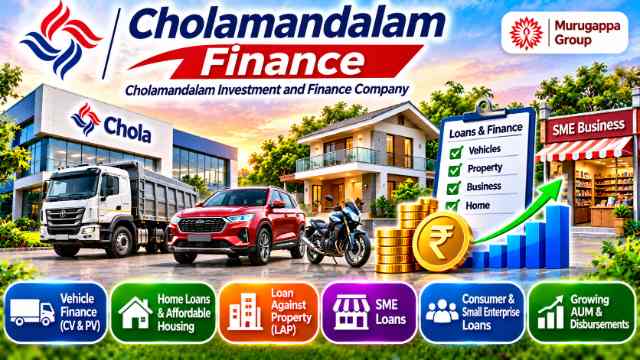
Explore Chola's vehicle finance, SME and housing loans, Q2 FY27 results, AUM growth, management guidance and key risks.
- Cholamandalam Investment and Finance Company, commonly known as Chola, is a non-banking finance company (NBFC) and part of the Murugappa Group.
- Chola serves commercial vehicle and passenger vehicle buyers, small businesses and home buyers.
- Vehicle finance is a major growth area for Chola.
What Chola Does
Cholamandalam Investment and Finance Company, commonly known as Chola, is a non-banking finance company (NBFC) and part of the Murugappa Group. Its business focuses on lending to individuals and businesses across vehicle finance, loan against property (LAP), SME loans, home loans and affordable housing, along with consumer and small enterprise loans.
Vehicle finance is an important part of its business. The company provides financing to commercial vehicle and passenger vehicle buyers, connecting its lending activity to vehicle purchases and demand.
Chola also lends against property and serves small businesses through its SME financing activities. Its home loan and affordable housing business extends its presence to individuals seeking finance for residential property. Consumer and small enterprise loans add further categories to its lending portfolio.
Unlike a bank that primarily relies on deposits as its funding base, Chola operates as an NBFC. Its business is centred on providing loans and earning income from those loans, alongside fees from its financial services.
Also Read: Vedanta: How Commodity Prices, Higher Volumes and Debt Reduction Drive Its Business
The range of lending categories gives Chola exposure to different customer requirements. Its performance depends on the demand for finance, the quality of borrowers and its ability to grow its loan portfolio while managing lending risks.
Customers and How Chola Makes Money
Chola serves commercial vehicle and passenger vehicle buyers, small businesses and home buyers. It provides finance to customers who need funding for vehicles, property and business requirements.
The company earns primarily through net interest income and fees. Net interest income is the difference between the interest it receives from borrowers and the interest it pays on its own funding. In simple terms, Chola earns interest on the loans it provides, while managing the cost of obtaining the money it lends.
Fees provide another source of income alongside interest earnings. The company’s overall performance therefore depends on the size of its loan portfolio, the income earned from lending and the costs associated with funding and operating the business.
Vehicle finance connects Chola to demand from commercial and passenger vehicle buyers. Loan against property and SME lending serve business customers, while home loans and affordable housing finance cater to individual borrowers.

Assets under management (AUM) is an important measure for understanding Chola’s business. It represents the total loan assets managed by the company. Growth in AUM indicates expansion in the lending portfolio, although the quality of those loans and the income they generate are equally important.
For investors, the key is to assess both the pace of lending growth and the company’s ability to manage credit risk. Rapid disbursement growth can expand the business, but sustainable performance depends on borrowers repaying their loans and the company maintaining control over loan losses.
Growth Drivers
Vehicle finance is a major growth area for Chola. Its lending to commercial and passenger vehicle buyers connects the company to vehicle demand. Management’s guidance for vehicle finance disbursement growth and AUM expansion provides an indication of the company’s expectations for this business during FY27.
Affordable housing is another important area. The company’s guidance for growth in this portfolio highlights its role in the broader lending strategy. Home loans and affordable housing finance allow Chola to serve individual borrowers alongside its vehicle and business lending customers.
SME loans and loan against property provide exposure to small businesses. These products add to the range of lending activities supporting the company’s overall AUM.
The improvement in the loan losses and provisions ratio is also relevant. Lower provisioning pressure can support profitability, although investors need to assess whether asset quality remains stable as the loan portfolio expands.
Competition and Risks
Asset quality is a central risk for Chola. Its lending portfolio includes vehicle buyers and small businesses, and the repayment capacity of these borrowers can be affected by changes in economic conditions. Weakness in these customer segments could increase loan losses and provisioning requirements.
Interest rates and funding costs are another important consideration. Chola earns net interest income, so changes in the cost of obtaining funds can influence the difference between interest earned on loans and interest paid on funding.
The company competes with banks and other NBFCs across vehicle finance, property-backed lending, SME loans and housing finance. Competition can affect lending opportunities and the terms on which finance is offered.
Also Read: REC: How Power and Infrastructure Financing Drive Its Business
Economic conditions and vehicle demand also influence the business. A weaker economic cycle or reduced demand for vehicles could affect borrowing activity and repayment performance.
Regulatory changes affecting NBFCs are another risk. Changes in the regulatory environment could influence how the company conducts its lending operations and manages its business.
The proposed capital raise also requires attention. Although the company has announced a proposal of up to ₹5,000 crore subject to approvals, investors should consider the potential dilution for existing shareholders alongside the intended benefits of raising capital.
What Investors Should Watch
Investors should first track disbursement growth and AUM expansion across Chola’s lending businesses. These measures indicate whether the company is continuing to grow its loan portfolio and how effectively it is executing its lending strategy.
Also Read: Punjab National Bank: How Deposits, Lending and Improving Asset Quality Drive Its Business
Asset quality deserves equal attention. The decline in the loan losses and provisions ratio is encouraging, but investors should monitor whether this improvement is sustained as lending expands, particularly in vehicle and small-business loans.
Net interest income and funding costs are also important. Changes in interest rates and the company’s cost of funding can influence lending margins and profitability.
The next area is performance against management’s FY27 guidance. Vehicle finance and affordable housing growth will help investors assess whether the company’s stated lending objectives are being achieved.
Finally, investors should follow the proposed capital raise, including the approvals, terms and potential effect on existing shareholders. The impact of any capital issuance should be assessed alongside the company’s growth requirements and financial performance.
Also Read: PFC: How Power Sector Financing and Renewable Energy Loans Drive Its Business
Conclusion
The next stage of its performance will depend on sustaining lending growth while protecting asset quality and managing funding costs. Investors should also monitor progress against management’s guidance and the proposed capital raise, particularly its implications for existing shareholders.
Financial Disclaimer: This article is for educational and informational purposes only. It is not investment advice or a recommendation to buy or sell Cholamandalam Investment and Finance shares. Investors should conduct independent research before making financial decisions.
Also Read: Muthoot Finance: How Gold Loans, Rising Gold Prices and Lending Growth Drive Its Business
Keep learning with OneTrader
Explore structured lessons and practical guides to build your market knowledge.

Need a laugh after all that money talk?
Paisa LOL: India's funniest finance page, with memes, comics, jokes and long funny stories.
