
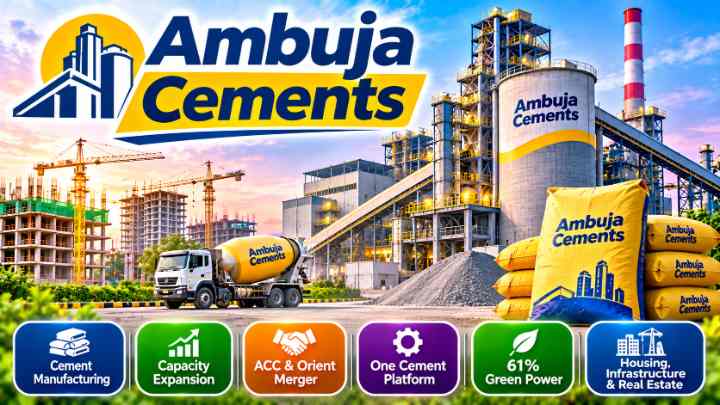
Explore Ambuja Cements' business model, Q2 FY27 results, capacity expansion, ACC merger, green power and key risks.
- Ambuja Cements is a cement manufacturer in the Adani portfolio, supplying cement and related products to customers across individual housing, construction, infrastructure and real estate markets.
- Ambuja Cements earns revenue by manufacturing and selling cement and related products.
- Capacity expansion is an important part of Ambuja Cements’ growth strategy.
What Ambuja Cements Does
Ambuja Cements is a cement manufacturer in the Adani portfolio, supplying cement and related products to customers across individual housing, construction, infrastructure and real estate markets. Its business is built around cement production and distribution, with sales reaching customers through trade and non-trade channels.
The company’s customer base includes individual home builders purchasing cement for residential construction, dealers serving local markets, and larger infrastructure and real estate projects. This gives Ambuja exposure to both retail construction demand and institutional cement consumption.
The group also includes ACC. Ambuja is progressing with the amalgamation of ACC and Orient Cement into the company. The proposed integration is expected to be earnings-per-share accretive, making the merger an important part of its longer-term corporate strategy.
Operational efficiency is another focus. Through its ‘One Cement Platform’ initiative, Ambuja is working towards a more integrated operating structure. The objective is to improve efficiency across its cement operations as the group progresses with its integration plans.
Also Read: Vedanta: How Commodity Prices, Higher Volumes and Debt Reduction Drive Its Business
The company is also increasing the contribution of green power to its operations. Green power accounted for 61% of its power mix, an important part of its efforts to change the energy profile of cement production.
Customers and How Ambuja Cements Makes Money
Ambuja Cements earns revenue by manufacturing and selling cement and related products. Its customers range from individual home builders and dealers to infrastructure developers and real estate projects.
The company reaches these customers through two principal channels: trade and non-trade. Trade sales serve the dealer and retail distribution network, including customers purchasing cement for individual construction requirements. Non-trade sales cater to larger buyers and projects that procure cement directly.
The distinction between these channels matters when assessing demand. Retail construction activity influences trade sales, while infrastructure and real estate project requirements contribute to non-trade demand. A balanced performance across the channels can provide a broader view of the company’s market activity.

Sales volume is a key measure for a cement manufacturer because it shows the quantity of cement sold. Pricing, product mix and production costs then influence how effectively those sales translate into revenue and operating profit.
Ambuja’s group structure is also relevant to understanding its business. The ongoing amalgamation involving ACC and Orient Cement is intended to bring the businesses under Ambuja, while the One Cement Platform initiative focuses on operating efficiency across the group.
Growth Drivers
The proposed amalgamation of ACC and Orient Cement is another major development. The merger is expected to be EPS accretive, while the One Cement Platform initiative is intended to improve efficiency across the combined operating structure. How effectively Ambuja executes the integration will be important to the benefits it can ultimately realise.
The company’s trade channel also showed positive momentum during the quarter, with trade volumes growing despite the slight decline in overall sales volume. Continued demand from individual home builders and dealers will therefore be an important part of its growth performance.
Green power is another area of operational development. Its growing contribution to the company’s power mix is relevant in an energy-intensive industry such as cement manufacturing.
Also Read: Shree Cement: How Premium Products, Sales Growth and Cost Management Drive Its Business
Together, capacity additions, integration and operating efficiency form the main elements of Ambuja’s expansion plans. Their contribution will depend on successful implementation and the company’s ability to translate production and sales activity into stronger profitability.
Competition and Risks
Ambuja Cements operates in a competitive market, with UltraTech and other cement producers competing for customers and projects. Competition can influence pricing and the company’s ability to protect margins, particularly when demand conditions are uneven.
The proposed merger also brings execution considerations. Integrating ACC and Orient Cement into Ambuja requires the company to progress with the amalgamation and its One Cement Platform initiative. The expected benefits depend on effective implementation.
Demand seasonality is another factor. Cement consumption can vary with seasonal and external conditions, affecting sales volumes and capacity utilisation. The slight decline in overall volume during the quarter highlights why investors should monitor demand rather than relying only on capacity expansion plans.
Flat overall volumes are also worth watching. Growth in trade sales is encouraging, but the company needs to sustain demand across its channels to support revenue and operating performance.
What Investors Should Watch
The next area is EBITDA margin and per-tonne profitability. Higher fuel, logistics and packaging costs affected operating performance during the quarter. Investors should monitor whether these pressures ease and whether improved efficiency translates into better margins.
Also Read: REC: How Power and Infrastructure Financing Drive Its Business
Capacity commissioning and ramp-up are also important. The company has expanded its production base, and the next step is to assess how effectively the additional capacity is brought into operation and contributes to sales.
Progress on the ACC and Orient Cement amalgamation deserves attention. Investors should follow the execution of the merger and the implementation of the One Cement Platform initiative, particularly in relation to the expected EPS accretion and efficiency objectives.
Finally, the contribution of green power and the company’s ability to manage operating costs will remain relevant to its performance. Investors should assess these developments alongside demand, pricing and competition rather than viewing capacity growth in isolation.
Conclusion
Also Read: Punjab National Bank: How Deposits, Lending and Improving Asset Quality Drive Its Business
The sharp decline in reported profit was influenced by the unusually high tax-related base in the previous-year quarter. Going forward, the important factors will be demand recovery, cost control, capacity ramp-up and execution of the ACC and Orient Cement amalgamation. These will determine how effectively the company converts its expansion plans into sustainable operating and earnings growth.
Financial Disclaimer: This article is for educational and informational purposes only. It is not investment advice or a recommendation to buy or sell Ambuja Cements shares. Investors should conduct independent research before making financial decisions.
Keep learning with OneTrader
Explore structured lessons and practical guides to build your market knowledge.

Need a laugh after all that money talk?
Paisa LOL: India's funniest finance page, with memes, comics, jokes and long funny stories.
