
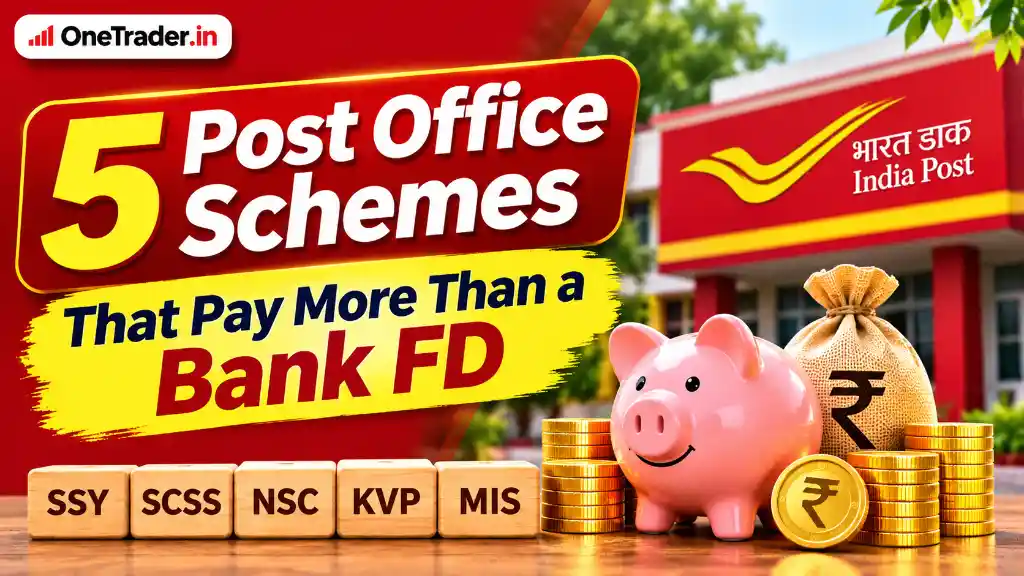
Bank fixed deposits remain a popular choice for Indian savers who want predictable returns without taking stock market risks. However, several government-backed Post Office small savings schemes currently offer interest rates that are higher than those available on many conventional bank fixed deposits.
For the October to December 2026 quarter, the Finance Ministry kept all small savings interest rates unchanged. This marks the tenth consecutive quarter without a revision. Five schemes currently offer rates between 7.4% and 8.2%, although eligibility, investment duration, interest payment frequency and taxation differ.
In simple words Post Office savings schemes can offer better interest rates than many traditional bank FDs, with government backing. However, not every scheme suits every investor, and some have eligibility conditions, lock-in periods or different taxation rules.
1. Sukanya Samriddhi Yojana: 8.2% Interest
Sukanya Samriddhi Yojana (SSY) is designed specifically for parents and guardians saving for a girl child’s future. It currently offers 8.2% annual interest, making it one of the highest-paying small savings options.
Also Read: Recurring Deposit vs SIP: Which Is Better for Regular Monthly Savings?
The maximum deposit is ₹1.5 lakh per financial year. The scheme is intended for long-term savings towards a girl’s education and future financial requirements.
The main advantage is its tax treatment. Interest earned under Sukanya Samriddhi Yojana is tax-free. However, it is not a general-purpose savings account because only eligible girl children can be covered, and the investment follows the scheme’s prescribed withdrawal and maturity conditions.
Who should consider it: Parents and guardians planning long-term savings for an eligible girl child.
2. Senior Citizens Savings Scheme: 8.2% Interest
The Senior Citizens Savings Scheme (SCSS) currently offers 8.2% annual interest. It is designed for eligible senior citizens who want regular income from their savings.
Also Read: Sinking Funds Explained: How to Save for Expenses Before They Arrive
Unlike schemes that accumulate interest until maturity, SCSS pays interest quarterly. This makes it useful for retirees who want periodic cash flow without depending entirely on bank FD interest payments.
The maximum investment limit is ₹30 lakh. The scheme has a five-year tenure, with an extension facility subject to applicable rules.
One important consideration is taxation. SCSS interest is taxable according to the investor’s income tax slab, and applicable TDS rules may apply.
Who should consider it: Eligible senior citizens looking for regular quarterly interest income and government-backed savings.
Also Read: High-Yield Savings Account vs Money Market Account: What’s the Difference?
3. National Savings Certificate: 7.7% Interest
The National Savings Certificate (NSC) offers 7.7% annual interest with a five-year investment period.
Its interest is compounded annually and paid at maturity. This means investors do not receive regular monthly or quarterly income. Instead, the investment grows through compounding until the certificate matures.
NSC has no maximum investment limit, making it an option for savers who want to accumulate money over a fixed period.

The main consideration is liquidity. Investors should be comfortable keeping their money invested for five years rather than depending on regular withdrawals. Interest is taxable according to the investor’s income tax slab.
Also Read: Certificate of Deposit (CD) vs Fixed-Rate Savings Bond: How Do They Work?
Who should consider it: Individuals looking for a five-year savings option with compounded returns rather than periodic income.
4. Kisan Vikas Patra: 7.5% Interest
Kisan Vikas Patra (KVP) currently offers 7.5% annual interest. Its key feature is straightforward: the invested money doubles in 115 months.
There is no maximum investment limit. This makes KVP suitable for savers who prefer a clearly defined long-term savings target.
However, the investment requires patience. The doubling period is 9 years and 7 months, so it is not suitable for people who may need their money in the near future.
Also Read: How Much Retirement Corpus Do You Need? A Complete Retirement Planning Guide
Interest is taxable according to the investor’s income tax slab.
Who should consider it: Long-term savers who want a government-backed instrument with a defined doubling period and do not need immediate access to their investment.
5. Post Office Monthly Income Scheme: 7.4% Interest
The Post Office Monthly Income Scheme (MIS) offers 7.4% annual interest and is designed for people who prefer regular income from their savings.
Unlike NSC and KVP, where returns accumulate over time, MIS pays interest monthly. This can make it useful for households looking for a predictable supplementary income stream.
Also Read: How to Build a ₹1 Crore Corpus From Your Salary: A Practical Wealth-Building Plan
The scheme has a five-year tenure. Its biggest attraction is the monthly interest payment, although the interest earned is taxable according to the investor’s income tax slab.
Investors should also consider the applicable deposit limits and the possibility that monthly interest may need to be reinvested if their objective is long-term wealth accumulation.
Who should consider it: Savers who prioritise monthly income over compounding and are comfortable with a five-year investment period.
Post Office Schemes vs Bank FDs: Interest Rate Comparison
The current rates show why small savings schemes deserve consideration alongside conventional bank deposits.
Also Read: How to Choose a High-Yield Savings Account
| Scheme or deposit | General rate | Senior citizen rate |
|---|---|---|
| Sukanya Samriddhi Yojana | 8.20% | Not applicable |
| Senior Citizens Savings Scheme | 8.20% | 8.20% |
| National Savings Certificate | 7.70% | 7.70% |
| Kisan Vikas Patra | 7.50% | 7.50% |
| Post Office Monthly Income Scheme | 7.40% | 7.40% |
| SBI 5-year FD | 6.05% | 7.05% |
| HDFC Bank FD, 5 years 1 day to 10 years | 6.60% | 7.10% |
| ICICI Bank FD, 5 to 10 years | 6.50% | Not specified here |
Bank FD rates are for the stated tenures and are subject to revision. HDFC Bank’s comparison rates are effective from 4 November 2026.
The comparison shows that the five Post Office schemes offer higher rates than the general-customer FD rates listed above. SCSS also offers a higher rate than the senior citizen FD rates shown.
However, this does not mean every Post Office scheme beats every bank deposit. Some small finance banks offer higher FD rates, and select senior citizen deposits at certain banks have reached 8.60% on specific tenures following November revisions.
There are also other government-backed savings options worth comparing. The five-year Post Office Time Deposit offers 7.5%, PPF offers 7.1%, the Post Office Recurring Deposit offers 6.7%, and Post Office savings accounts offer 4%.
Also Read: NPS for NRIs: Who Can Invest, Tax Benefits and Withdrawal Rules
Government Backing vs Bank Deposit Insurance
Interest rates should not be the only factor when comparing savings products. The safety structure also matters.
Post Office small savings schemes carry government backing. Bank deposits, on the other hand, are insured up to ₹5 lakh per depositor per bank.
This distinction is particularly relevant for people placing substantial amounts in fixed deposits. A bank offering a higher rate does not automatically make it the better choice for someone whose primary objective is capital safety.
Investors should also compare tenure, withdrawal conditions, tax treatment and the reliability of the institution before committing their savings.
Also Read: Why You Should Pay Yourself First | Smart Money Habit Explained – Onetrader
Taxation: What Investors Should Know
Tax treatment differs across these schemes.
Sukanya Samriddhi Yojana interest is tax-free. However, interest from NSC, KVP, MIS and SCSS is taxable according to the investor’s applicable income tax slab.
SCSS and other applicable schemes may also be subject to TDS rules. Investors should consider the post-tax return rather than comparing interest rates alone.
A scheme offering 8.2% interest may not necessarily deliver the same effective return to investors in different tax brackets.
Also Read: Where is Indian Investors’ Wealth? Gold, Real Estate, or Markets?
How to Choose the Right Scheme
The right choice depends on why you are saving and when you need the money.
- For a girl’s future: Sukanya Samriddhi Yojana offers 8.2% interest with tax-free interest earnings, subject to eligibility.
- For retirement income: SCSS offers 8.2% with quarterly interest payments for eligible senior citizens.
- For five-year accumulation: NSC offers 7.7% with annual compounding and payment at maturity.
- For long-term doubling: KVP offers a defined 115-month doubling period.
- For monthly income: MIS offers 7.4% with monthly interest payments.
Small savings rates are reviewed every quarter. Although the October to December 2026 rates remain unchanged, the next revision can take effect from 1 January 2027. Investors planning a new deposit should check the applicable rate and scheme conditions before investing.
Key Takeaways
- Five Post Office schemes currently offer interest rates between 7.4% and 8.2%.
- Sukanya Samriddhi Yojana and SCSS offer the highest rate at 8.2%.
- NSC provides 7.7% through annual compounding over five years.
- KVP offers 7.5% and doubles the investment in 115 months.
- MIS pays 7.4% interest monthly.
- Many conventional bank FD rates are lower, although some small finance banks offer higher rates.
- Post Office schemes carry government backing, while bank deposits have insurance protection up to ₹5 lakh per depositor per bank.
- Taxation, eligibility and liquidity should be considered before choosing a scheme.
Disclaimer: This article is for informational and educational purposes only. Interest rates, eligibility, withdrawal conditions and tax treatment are subject to applicable government rules and revisions. Investors should verify the latest scheme conditions and consider their financial goals and tax position before investing. This article does not constitute investment advice.
Keep learning with OneTrader
Explore structured lessons and practical guides to build your market knowledge.

Need a laugh after all that money talk?
Paisa LOL: India's funniest finance page, with memes, comics, jokes and long funny stories.
