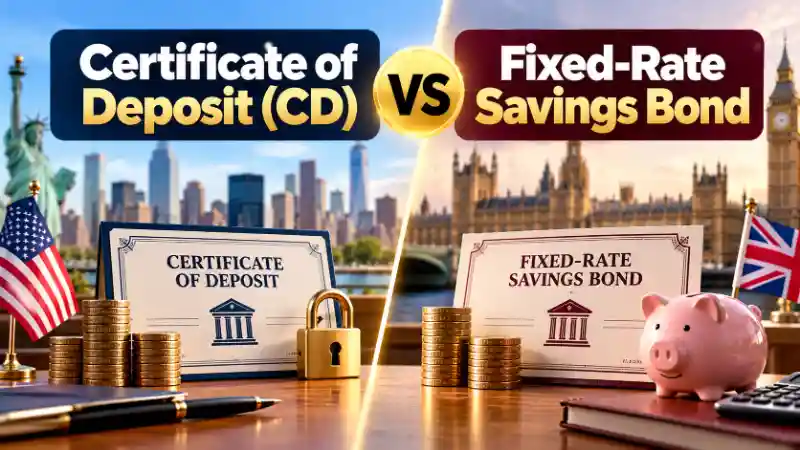
Saving money for a specific financial goal often involves balancing interest rate certainty against access to cash. In the United States, certificates of deposit (CDs) are commonly used to earn interest over a defined period. In the United Kingdom, fixed-rate savings bonds offer a similar arrangement through banks and building societies.
Both products generally involve depositing money for an agreed term in exchange for a predetermined interest rate. However, early withdrawal restrictions, deposit protection, interest calculations and tax treatment differ between the two countries.
Understanding these differences is particularly relevant for households saving towards property purchases, education expenses or other financial commitments with predictable timelines.
What Is a Certificate of Deposit in the United States?
A certificate of deposit is a deposit product offered by banks and credit unions. With a traditional fixed-rate CD, customers deposit money for an agreed term while the financial institution pays interest according to the account agreement.
Also Read: Index Funds vs ETFs: Which Is Better for Long-Term Investing?
CD terms vary by provider and may range from a few months to several years. Traditional fixed-rate CDs generally maintain the agreed interest rate until maturity, although variable-rate, step-up and other specialised CD products also exist.
For example, a hypothetical $10,000 deposit earning 4.00% annual percentage yield (APY) would grow to approximately $10,400 after one year, assuming the stated APY applies throughout the period, interest remains deposited and no fees or withdrawals affect the balance.
Unlike an ordinary savings account, a traditional CD generally involves a commitment to leave the money deposited until maturity. Early withdrawals may result in contractual penalties.
What Is a Fixed-Rate Savings Bond in the UK?
A fixed-rate savings bond is generally a bank or building society deposit account that pays a predetermined interest rate over a specified term.
Also Read: How Much Retirement Corpus Do You Need? A Complete Retirement Planning Guide
Despite the word “bond,” these savings products should not be confused with corporate bonds, government bonds or other tradable debt securities. Their legal structure, risks and regulatory protections can be different.
UK savings providers commonly advertise the annual equivalent rate (AER), which expresses the annualised interest return under the stated compounding assumptions.
For example, a hypothetical £10,000 deposit earning 4.00% AER would generate approximately £400 over one year, assuming the applicable terms remain unchanged and interest is retained as required.
Many UK fixed-rate savings products restrict withdrawals until maturity. Some providers do not permit early access under ordinary circumstances, while others allow withdrawals subject to specific conditions or interest penalties.
Also Read: How to Build a ₹1 Crore Corpus From Your Salary: A Practical Wealth-Building Plan
How Do CD Interest Rates and Fixed-Rate Bond Returns Compare?
Traditional fixed-rate CDs and UK fixed-rate savings bonds provide greater certainty about nominal interest rates than variable-rate savings accounts.
Once a fixed-rate agreement is established, the contractual interest rate generally remains unchanged throughout the agreed term, subject to the product’s conditions.
However, products with identical advertised rates may produce different outcomes depending on interest payment schedules, compounding, account charges and the treatment of withdrawn interest.
US banks commonly advertise APY, while UK savings providers use AER. Both measures help express annualised interest earnings, but account-specific conditions remain important when comparing deposits.
Also Read: How to Choose a High-Yield Savings Account
A fixed interest rate also does not guarantee protection against inflation. If consumer prices rise faster than the after-tax return on savings, the money’s purchasing power can decline despite earning interest.
Early Withdrawal Penalties and Access Restrictions
Access to money before maturity is one of the most important differences between fixed-term savings products.
In the United States, traditional CDs generally impose an early withdrawal penalty. The amount and calculation method depend on the institution and account agreement. Penalties may be expressed as a specified period of interest, and some arrangements can reduce the principal returned if the penalty exceeds interest already earned.
Certain institutions offer no-penalty CDs, allowing withdrawals under defined conditions. These accounts may have different rates or access requirements from traditional CDs.
Also Read: NPS for NRIs: Who Can Invest, Tax Benefits and Withdrawal Rules
UK fixed-rate savings bonds may impose stricter restrictions. Some accounts prohibit early withdrawals except in exceptional circumstances, while others permit access subject to contractual penalties.
Consequently, the maturity date and early withdrawal provisions are important parts of the product agreement, not merely secondary account features.
FDIC Insurance and FSCS Protection
Deposit protection is an important consideration when evaluating fixed-term savings accounts.
In the United States, eligible CDs at FDIC-insured banks receive protection up to $250,000 per depositor, per insured bank, per ownership category. Deposits in the same ownership category at the same bank are combined when determining coverage, including savings accounts and CDs.
Also Read: Why You Should Pay Yourself First | Smart Money Habit Explained – Onetrader
Qualifying CDs issued by federally insured credit unions receive comparable protection through the National Credit Union Share Insurance Fund, administered by the NCUA.
In the United Kingdom, eligible fixed-rate savings deposits are protected by the Financial Services Compensation Scheme (FSCS) up to £120,000 per eligible person, per authorised firm. This limit took effect on December 1, 2025.
Where different banking brands share the same relevant authorisation, eligible deposits are generally combined for FSCS protection purposes.
These protections apply to qualifying deposits, not automatically to corporate bonds, investment securities or other products with similar names.
Also Read: 80/20 Rule in Stock Market – The Secret Every Trader Must Know
How Are CDs and Fixed-Rate Savings Bonds Taxed?
In the United States, interest earned on ordinary taxable CDs is generally subject to federal income tax. Taxpayers must report taxable interest even when they do not receive Form 1099-INT.
For CDs with maturities exceeding one year, IRS original issue discount rules generally require a portion of the interest to be included in taxable income annually, even when payment is deferred until maturity.
For CDs maturing within one year, interest is generally included when received or made available without a substantial penalty. Individual circumstances and account structures can affect the treatment.
In the United Kingdom, interest from ordinary fixed-rate savings bonds generally forms part of taxable savings income.
Also Read: Where is Indian Investors’ Wealth? Gold, Real Estate, or Markets?
For the 2026–27 tax year, the Personal Savings Allowance is £1,000 for basic-rate taxpayers, £500 for higher-rate taxpayers and £0 for additional-rate taxpayers. Other allowances, including the starting rate for savings, may apply depending on income.
The timing of taxation can depend on when interest becomes available. Interest credited annually to an accessible account may be taxable in that year, while interest that cannot be accessed until maturity may arise for tax purposes when it becomes available.
Interest earned within a qualifying Cash ISA is generally exempt from UK income tax. The overall ISA subscription allowance for 2026–27 is £20,000, subject to eligibility and applicable rules.
What Happens When a Fixed-Term Deposit Matures?
When a traditional CD or fixed-rate savings bond reaches maturity, the institution generally makes the principal and applicable interest available according to the account agreement.
Some US CDs automatically renew into another fixed-term account unless customers provide alternative instructions. For automatically renewing consumer CDs, applicable disclosure rules require information about renewal policies and any grace period.
The renewed CD may carry a different interest rate from the original deposit. Other products may transfer the balance to another account or stop earning interest after maturity.
UK fixed-rate savings providers also establish maturity instructions, which may include repayment to a nominated account or an option to enter a new savings agreement.
Understanding these arrangements helps distinguish the certainty of a fixed nominal interest rate from the restrictions that may apply to accessing money before or after maturity.
OneTrader Disclaimer: This article is provided for educational and informational purposes only and does not constitute financial, investment, tax or legal advice. OneTrader is not registered with SEBI or as an investment adviser with US or UK financial regulatory authorities. Interest rates, deposit protection limits, early withdrawal penalties, account conditions and tax regulations may change. Readers should independently verify current product terms and applicable regulations and consult qualified financial professionals where appropriate.
Keep learning with OneTrader
Explore structured lessons and practical guides to build your market knowledge.