
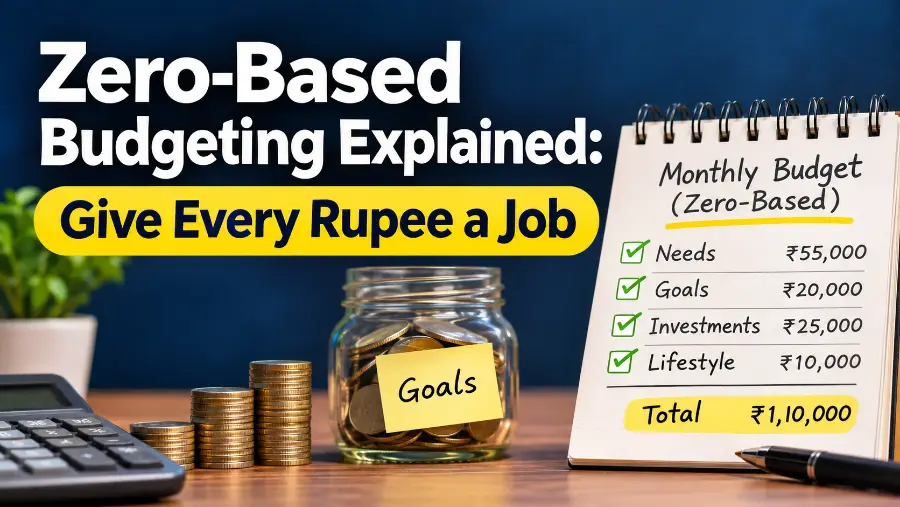
Managing money is not just about earning more. It is also about knowing where every rupee goes. Many households receive their salaries, pay bills, handle daily expenses and invest whatever remains. The problem is that there is often very little left to save because spending happens without a clear plan.
Zero-based budgeting offers a more disciplined approach. Instead of waiting until the end of the month to see how much money remains, you decide in advance how your entire income will be used. Every rupee gets a specific purpose, whether it is paying expenses, building savings, investing or reducing debt.
In simple words
Zero-based budgeting means allocating your entire monthly income to different purposes until your income minus planned expenses, savings, investments and debt payments equals zero. It does not mean spending all your money. It means accounting for every rupee before spending it.
Also Read: Practical Money Management Rules That Actually Work for Indian Investors and Traders
What Is Zero-Based Budgeting?
Zero-based budgeting is a personal finance method in which you assign every rupee of your monthly income to a category. These categories can include rent, groceries, electricity, insurance, loan repayments, emergency savings, investments and entertainment.
The central principle is simple:
Monthly Income − Total Allocations = ₹0
For example, if your take-home salary is ₹60,000, you should plan how the entire ₹60,000 will be distributed. Even money intended for future savings or investments must have a place in the budget.
Also Read: CIBIL Score: Why Your Credit Score Matters More Than You Think
The objective is not to restrict every purchase but to ensure that spending reflects your financial priorities.
How Does Zero-Based Budgeting Work?
The process starts with your expected monthly take-home income. List all essential expenses, financial commitments and discretionary spending. Then allocate the remaining amount towards savings, investments and other goals.
Here is an illustrative monthly budget for someone earning ₹60,000.
| Category | Monthly Allocation |
|---|---|
| Rent | ₹12,000 |
| Groceries | ₹6,000 |
| Utilities and internet | ₹2,500 |
| Transport | ₹4,000 |
| Insurance | ₹2,500 |
| Loan repayment | ₹5,000 |
| Entertainment and dining | ₹3,000 |
| Emergency fund | ₹5,000 |
| Mutual fund investments | ₹12,000 |
| Short-term savings | ₹5,000 |
| Miscellaneous | ₹3,000 |
| Total | ₹60,000 |
In this example, the entire salary has been assigned a purpose. Nothing is left unallocated.

Steps to Create a Zero-Based Budget
1. Calculate Your Monthly Income
Start with your actual take-home salary after taxes and deductions. Include other reliable income sources, such as rental income or regular freelance earnings.
If your income changes every month, use a conservative estimate rather than assuming you will receive your highest possible earnings.
2. List All Monthly Expenses
Identify fixed and variable expenses.
Fixed expenses generally remain similar every month, while variable expenses change depending on consumption and lifestyle.
| Fixed Expenses | Variable Expenses |
|---|---|
| Rent or home loan EMI | Groceries |
| Insurance premiums | Electricity |
| Loan repayments | Fuel and transport |
| School fees | Dining and entertainment |
Review bank statements and UPI transactions to understand your actual spending rather than relying entirely on estimates.
3. Allocate Money to Savings and Investments
Savings should not depend on what remains at the end of the month. Include emergency fund contributions, mutual fund SIPs, retirement investments and other financial goals in the initial budget.
This makes wealth creation a planned financial commitment rather than an occasional activity.
4. Assign Money to Discretionary Spending
Entertainment, shopping, dining and holidays are legitimate expenses. The important thing is to establish reasonable limits.
When a category reaches its monthly allocation, avoid spending more unless you deliberately adjust another category.
5. Review and Adjust Your Budget
Actual expenses will rarely match your estimates perfectly. Review your budget every week and make adjustments when necessary.
If grocery expenses increase, for example, you may reduce discretionary spending instead of withdrawing money allocated for investments.
Zero-Based Budgeting vs Traditional Budgeting
Both methods help manage money, but their approach is different.
| Feature | Zero-Based Budgeting | Traditional Budgeting |
|---|---|---|
| Planning | Every rupee is allocated | Broad spending limits |
| Savings | Planned in advance | Often based on remaining income |
| Expense tracking | Detailed | Can be less detailed |
| Flexibility | Requires regular adjustments | Generally more flexible |
| Financial control | Higher visibility | Depends on spending discipline |
Traditional budgeting can work well for people with stable spending habits. Zero-based budgeting is particularly useful for those who want greater control over their monthly cash flow.
Advantages of Zero-Based Budgeting
The biggest advantage is financial visibility. You know exactly how much money is available for essential expenses, lifestyle spending and investments.
Other important benefits include:
- Better spending discipline: Planned allocations reduce unnecessary purchases.
- Consistent savings: Savings and investments become monthly priorities.
- Debt management: You can assign specific amounts towards outstanding loans.
- Goal tracking: Financial goals receive dedicated monthly allocations.
- Early identification of waste: Regular tracking helps identify subscriptions and expenses that can be reduced.
Common Mistakes to Avoid
Zero-based budgeting requires consistency, but it does not need to become complicated.
One common mistake is creating unrealistic spending limits. Setting an excessively low grocery or entertainment budget can make the system difficult to maintain.
Another mistake is ignoring irregular expenses such as vehicle servicing, annual insurance premiums, medical costs and festival spending. These expenses should be divided into monthly allocations so they do not disrupt the budget when they arise.
It is also important not to treat emergency savings as ordinary spending money. Keep emergency funds separate and use them for genuine financial emergencies.
Finally, avoid abandoning the budget because one category exceeds its limit. Adjust the remaining allocations and continue.
Is Zero-Based Budgeting Suitable for Everyone?
Zero-based budgeting can work for salaried employees, freelancers, families and people managing multiple financial commitments. It is particularly helpful when income is limited, expenses are rising or savings goals need greater attention.
However, people with irregular income may need to maintain a larger cash buffer and build their budgets around conservative income estimates.
The method also requires regular tracking. Someone who prefers minimal financial administration may find a simpler percentage-based budgeting system easier to maintain.
Key Takeaways
- Zero-based budgeting assigns every rupee of income a specific purpose.
- The objective is to make monthly income minus all allocations equal zero.
- Savings, investments and debt repayments should be included in the budget.
- Track actual spending and adjust allocations when expenses change.
- Plan for irregular expenses instead of allowing them to disrupt monthly finances.
- Consistency matters more than creating a perfect budget.
Zero-based budgeting is ultimately about making deliberate financial decisions. When every rupee has a job, it becomes easier to control spending, build savings, reduce debt and work towards long-term financial independence.
Financial Disclaimer: This article is for educational and informational purposes only. Budgeting requirements vary depending on individual income, expenses, financial commitments and goals. Readers should evaluate their personal circumstances before making financial decisions.
Keep learning with OneTrader
Explore structured lessons and practical guides to build your market knowledge.

Need a laugh after all that money talk?
Paisa LOL: India's funniest finance page, with memes, comics, jokes and long funny stories.
