
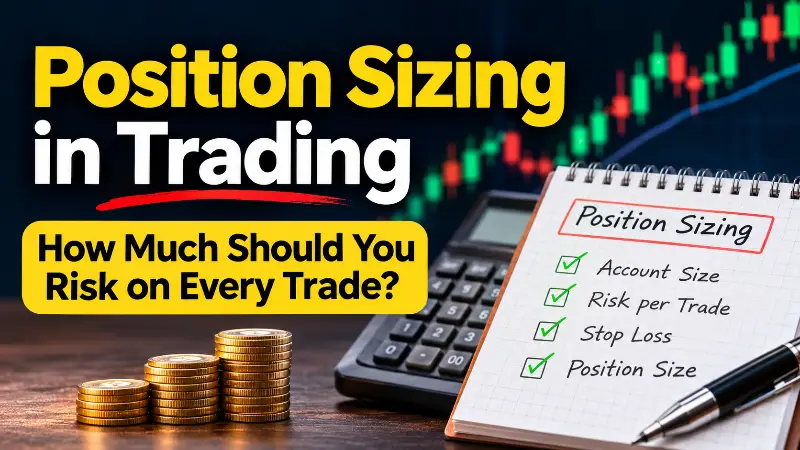
Every trader focuses on finding the right entry, identifying support and resistance, and predicting where a stock might move next. However, one important decision often determines whether a trading account survives over the long term: how much money should be risked on a single trade?
Position sizing is the process of deciding how many shares or lots to buy or sell based on account capital, acceptable risk and stop-loss distance. Even a good trading strategy can produce poor results when position sizes are too large. Managing this calculation consistently helps traders control losses and protect their capital.
In simple words
Position sizing tells you how many shares or lots you should trade without risking more than your predetermined loss limit. Instead of deciding quantity based on confidence, you calculate it using your capital and stop-loss distance.
Also Read: Risks in ETFs Explained – Tracking Error, Liquidity & Market Risk
What Is Position Sizing in Trading?
Position sizing determines the quantity of a financial instrument a trader should buy or sell in a particular trade.
For example, suppose you have a trading capital of ₹2 lakh and are willing to risk 1% on each trade. Your maximum acceptable loss is ₹2,000.
If your stop-loss is ₹20 below your entry price, you can purchase 100 shares.
The calculation is straightforward:
Position Size = Maximum Risk Amount ÷ Risk Per Share
This approach ensures that the potential loss remains within your predefined limit if the stop-loss is executed at the expected price.
How Much Should You Risk Per Trade?
Many traders use a risk-per-trade range of 0.5% to 2% of their trading capital. The appropriate percentage depends on experience, strategy, market conditions and financial capacity.
| Risk per trade | Risk on ₹1 lakh capital |
|---|---|
| 0.5% | ₹500 |
| 1% | ₹1,000 |
| 1.5% | ₹1,500 |
| 2% | ₹2,000 |
| 3% | ₹3,000 |
For beginners, risking 0.5% to 1% per trade is a conservative starting framework. Experienced traders may use higher limits, but increasing risk does not automatically improve profitability.
The objective is not to maximise the amount risked. It is to remain in the market long enough for a trading strategy to demonstrate its edge.
How to Calculate Position Size
Consider a trader with ₹2 lakh in trading capital who follows a 1% risk rule.
The calculation involves three steps.
Step 1: Calculate the maximum risk amount

Trading capital × Risk percentage
₹2,00,000 × 1% = ₹2,000
Step 2: Identify the stop-loss distance
Suppose a stock is purchased at ₹500 with a stop-loss at ₹480.
Risk per share = ₹500 – ₹480 = ₹20.
Step 3: Calculate the quantity
₹2,000 ÷ ₹20 = 100 shares.
The resulting trade is:
| Particulars | Amount |
|---|---|
| Trading capital | ₹2,00,000 |
| Risk percentage | 1% |
| Maximum risk | ₹2,000 |
| Entry price | ₹500 |
| Stop-loss | ₹480 |
| Risk per share | ₹20 |
| Quantity | 100 shares |
| Total trade value | ₹50,000 |
If the stop-loss executes at ₹480, the expected loss is ₹2,000, excluding brokerage, taxes, slippage and other charges.
Position Sizing Based on Stop-Loss Distance
One important principle of position sizing is that quantity should change according to the stop-loss distance.
A wider stop-loss requires a smaller position, while a narrower stop-loss allows a larger position for the same predefined monetary risk.
Consider the same ₹2,000 risk limit:
| Stop-loss distance | Maximum quantity |
|---|---|
| ₹10 | 200 shares |
| ₹20 | 100 shares |
| ₹25 | 80 shares |
| ₹40 | 50 shares |
| ₹50 | 40 shares |
This is why traders should identify their stop-loss based on market structure, price action or technical invalidation before calculating the position size.
A stop-loss should not be artificially tightened just to purchase more shares. It must represent a genuine level where the original trade setup becomes invalid.
Understanding the 1% Risk Rule
The 1% risk rule means that a trader limits the planned loss on an individual trade to 1% of the current trading capital.
Suppose the account starts with ₹1 lakh. The initial risk limit is ₹1,000.
If the account grows to ₹1.10 lakh, the corresponding 1% risk becomes ₹1,100. If the account declines to ₹90,000, the risk limit reduces to ₹900.
This creates a dynamic risk management approach that adjusts position sizes according to account performance.
However, the 1% rule is a guideline, not a guarantee against losses. Multiple losing trades can still reduce capital.
How Position Sizing Protects Trading Capital
The biggest advantage of position sizing becomes visible during consecutive losing trades.
Consider an account starting with ₹1 lakh. The following table illustrates the impact of repeated losses at different risk levels, assuming the risk percentage is recalculated using the remaining capital.
| Consecutive losses | 1% risk | 2% risk | 5% risk |
|---|---|---|---|
| 1 | ₹99,000 | ₹98,000 | ₹95,000 |
| 5 | ₹95,099 | ₹90,392 | ₹77,378 |
| 10 | ₹90,438 | ₹81,707 | ₹59,874 |
| 15 | ₹86,007 | ₹73,853 | ₹46,329 |
The difference becomes significant as losing trades accumulate.
Smaller risk percentages reduce the impact of a losing streak and make it easier to recover without taking unnecessary risks.
Common Position Sizing Mistakes Traders Should Avoid
Increasing quantity after a loss: Increasing position size to recover previous losses can quickly damage an account. Every trade should follow its predefined risk limit.
Using the same quantity for every trade: Different stocks have different price movements and stop-loss distances. Fixed quantities can create inconsistent monetary risk.
Ignoring brokerage and slippage: Actual losses can exceed the planned amount because of execution differences, particularly during volatile market conditions and gap-down openings.
Taking oversized positions in F&O: Futures and options involve leverage, margin requirements and potentially rapid losses. Traders should calculate exposure and maximum possible loss carefully rather than treating margin as available risk capital.
Moving stop-losses further away: Expanding a stop-loss after entering a trade increases the original risk and undermines the position-sizing calculation.
Position Sizing and Risk-Reward Ratio
Position sizing controls how much money is at risk, while the risk-reward ratio compares potential profit with potential loss.
For example, if a trader risks ₹2,000 to target ₹4,000, the trade has a 1:2 risk-reward ratio.
| Risk amount | Risk-reward | Potential target |
|---|---|---|
| ₹1,000 | 1:1 | ₹1,000 |
| ₹1,000 | 1:2 | ₹2,000 |
| ₹1,000 | 1:3 | ₹3,000 |
| ₹2,000 | 1:2 | ₹4,000 |
A favourable risk-reward ratio does not guarantee profitability. Win rate, execution quality, trading costs and consistency also matter.
Traders should evaluate these factors together rather than relying on a high risk-reward ratio alone.
Key Takeaways
- Position sizing determines how many shares or lots to trade based on predefined risk.
- Beginners can consider 0.5% to 1% risk per trade as a conservative starting framework.
- Calculate the maximum monetary risk before entering a trade.
- Determine the stop-loss using technical analysis, not the desired position size.
- Wider stop-loss distances require smaller quantities.
- Avoid increasing position sizes to recover previous losses.
- Include brokerage, taxes, slippage and market volatility in risk planning.
- Consistent position sizing helps protect trading capital over the long term.
Financial Disclaimer: This article is for educational and informational purposes only and should not be considered investment advice or a recommendation to buy or sell any financial instrument. Trading in equities, futures and options involves market risk and the possibility of capital loss. Traders should assess their financial situation, risk tolerance and trading experience before making investment decisions.
Keep learning with OneTrader
Explore structured lessons and practical guides to build your market knowledge.

Need a laugh after all that money talk?
Paisa LOL: India's funniest finance page, with memes, comics, jokes and long funny stories.
