Titan Company has grown from a watch manufacturer into one of India’s leading branded consumer businesses.
- Titan operates across jewellery, watches, eyewear and other lifestyle categories.
- Titan serves jewellery buyers, watch consumers, eyewear customers and shoppers looking for lifestyle products.
- Jewellery remains Titan’s biggest growth opportunity.
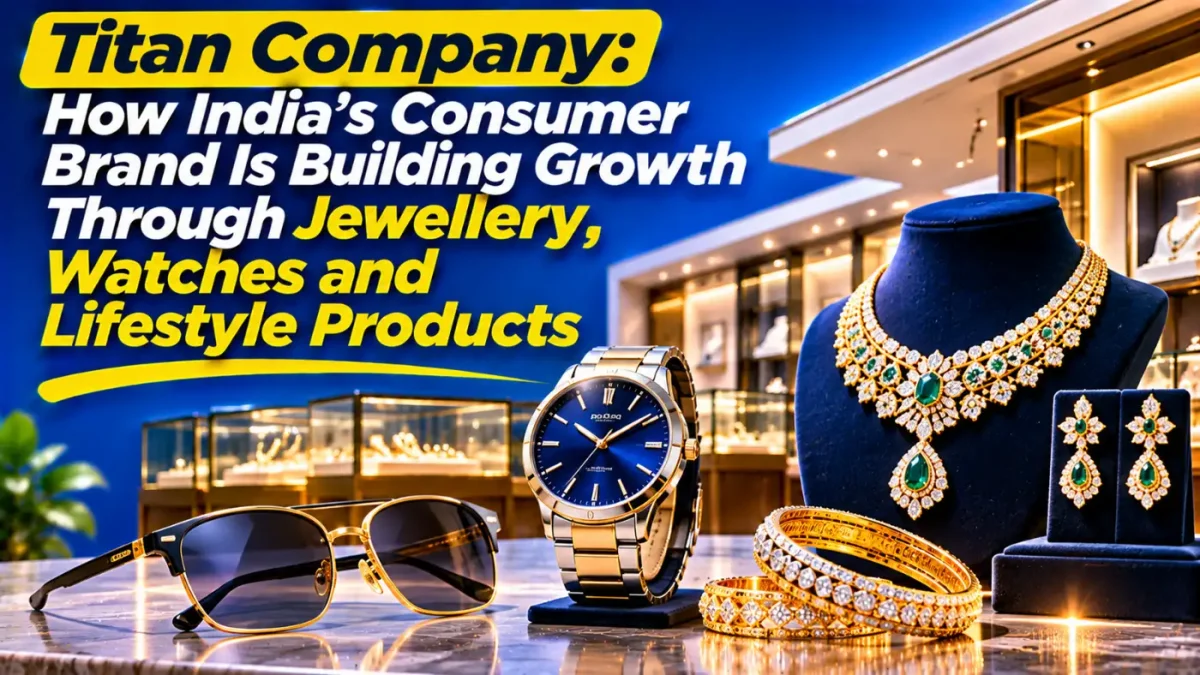
Titan Company has grown from a watch manufacturer into one of India’s leading branded consumer businesses. Jewellery is now its largest business, supported by watches, eyewear, fragrances and other lifestyle products. Its brands, retail network and customer trust give it a strong position in organised retail, particularly in a jewellery market where purchases are closely linked to weddings, festivals and personal savings.
Titan’s strategy is to expand its established brands, attract customers to premium products and build a larger international jewellery business. The opportunity is substantial, but performance remains sensitive to gold prices, consumer spending and the cost of expanding its retail network.
What Titan Does
Titan operates across jewellery, watches, eyewear and other lifestyle categories.
Jewellery is its largest business, with brands including Tanishq, Mia, Zoya and CaratLane. Tanishq serves a broad jewellery market, Mia focuses on contemporary designs, Zoya targets the luxury segment, and CaratLane has a strong online and omnichannel presence. Titan has also expanded internationally through its acquisition of a majority stake in Damas Jewellery, strengthening its presence in the Gulf region.
Also Read: Apollo Hospitals: How India’s Healthcare Giant Is Building Growth
Its watches business includes Titan, Fastrack, Sonata and international brands sold through Helios. The portfolio ranges from affordable everyday watches to premium and luxury products. The eyewear business operates through Titan Eye+, offering prescription glasses, sunglasses, lenses and related services.
Other businesses include fragrances under Skinn, women’s bags under IRTH, ethnic wear through Taneira and engineering and automation solutions through Titan Engineering and Automation Limited. These activities are smaller than jewellery but broaden the company’s consumer and industrial presence.
Customers and How Titan Makes Money
Titan serves jewellery buyers, watch consumers, eyewear customers and shoppers looking for lifestyle products. Its customers range from mass-market buyers to premium and luxury consumers. Weddings, festivals, gifting and personal purchases are important demand occasions, particularly for jewellery and watches.
The company earns most of its revenue by selling branded products through its own stores, franchise outlets, dealers, online platforms and other retail partners. Jewellery sales generate the largest share of revenue. Titan earns from gold, diamond and studded jewellery, with product mix and making charges influencing the profitability of sales.

Also Read: Trent: How Westside and Zudio Are Driving Growth
Watches and eyewear generate revenue through branded products, accessories and retail services. Premium watches and branded eyewear can support stronger realisations, while a wide range of price points helps the company reach different customer groups.
Titan’s retail network is central to its model. Stores help customers assess product quality, design and fit, particularly for high-value jewellery purchases. Digital platforms and omnichannel services complement physical outlets and support customer discovery, repeat purchases and exchange programmes.
Growth Drivers
Jewellery remains Titan’s biggest growth opportunity. Organised retail, branded designs, trust in product quality and transparent pricing can help the company attract customers who previously purchased from local jewellers. Tanishq, Mia and CaratLane allow Titan to serve different customer preferences and price points.
Premiumisation is another important driver. Demand for diamond-studded jewellery, premium watches and branded eyewear can improve product realisations and strengthen margins. The company can also grow through new collections, exchange programmes and a wider range of designs.
International expansion offers a longer-term opportunity. Damas gives Titan a larger retail presence in the Gulf, while its existing international jewellery operations provide a platform to reach Indian diaspora and other customers. The success of this strategy will depend on integrating the acquired business and building consistent profitability.
Watches and eyewear provide additional growth beyond jewellery. Premium analogue watches, fashion-led products and organised optical retail can support repeat purchases and broaden Titan’s customer relationships.
Competition and Risks
Titan competes with Malabar Gold & Diamonds, Kalyan Jewellers, Joyalukkas and regional jewellers in the jewellery market. In watches, it faces brands such as Casio, Citizen, Fossil and Apple, alongside domestic competitors. In eyewear, competition includes Lenskart and established international brands.
Gold price volatility is a major risk. Higher prices can increase the value of jewellery sales but may also make purchases less affordable and affect volumes. Changes in customs duties, import rules and the cost of gold can influence margins and customer behaviour.
The jewellery business also requires substantial inventory and working capital. A sharp change in gold prices can affect inventory valuation and the amount of capital tied up in stock. Competition from local jewellers and online platforms can put pressure on pricing and customer acquisition costs.
International expansion introduces currency, regulatory and integration risks. Titan must also protect brand reputation and product quality as its store network grows. In watches and eyewear, changing consumer preferences and competition from technology-led products require continued innovation.
What Investors Should Watch
Jewellery growth, studded product sales and the contribution of Tanishq, Mia and CaratLane are central indicators for Titan. Investors should distinguish revenue growth caused by higher gold prices from growth in customer demand and volumes.
Operating margins deserve close attention, particularly after adjusting for customs-duty benefits and other exceptional accounting items. The performance of watches, eyewear and emerging businesses will show whether Titan is building meaningful growth beyond jewellery.
Store additions, same-store sales, inventory levels and working-capital requirements can indicate whether retail expansion is creating value. The Damas integration and international jewellery profitability are also important measures of the company’s global strategy.
Titan has strong consumer brands, a wide retail network and leadership in several organised lifestyle categories. Jewellery provides scale, while watches, eyewear and international expansion offer additional growth opportunities. The investment case depends on maintaining customer trust, protecting margins through gold price cycles and ensuring that new stores and acquisitions generate attractive returns.
Financial Disclaimer: This article is for educational and informational purposes only. It is not investment advice or a recommendation to buy or sell any security. Investors should review company disclosures, financial statements, risks and valuations and consult a qualified financial adviser before making investment decisions.
Keep learning with OneTrader
Explore structured lessons and practical guides to build your market knowledge.

Need a laugh after all that money talk?
Paisa LOL: India's funniest finance page, with memes, comics, jokes and long funny stories.