
Detailed Restaurant Brands Asia analysis covering Burger King India, business model, management strategy, financial performance, competitive moat, growth drivers, risks and long term outlook.
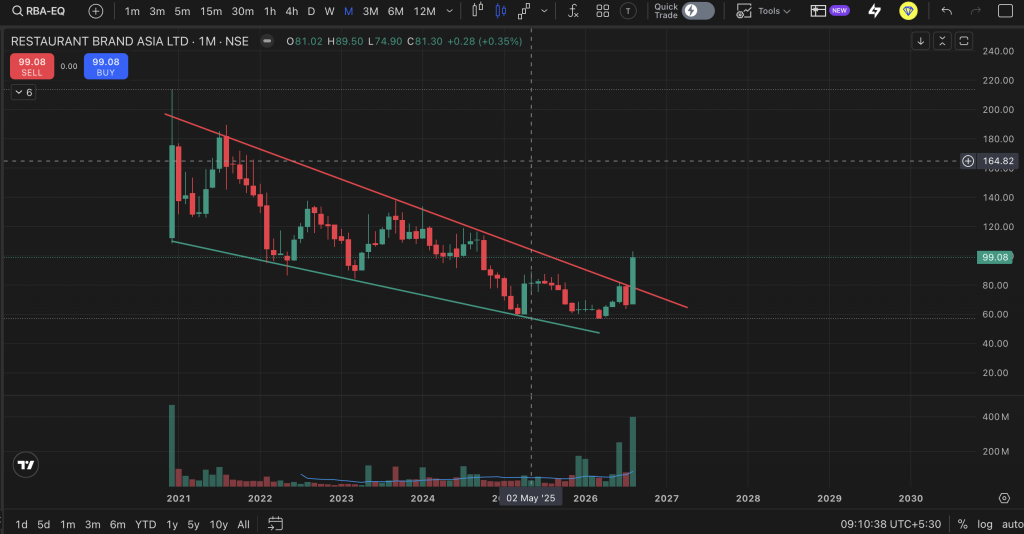
- Restaurant Brands Asia Ltd is one of the more interesting turnaround stories in India’s quick service restaurant sector.
- Restaurant Brands Asia operates as the master franchisee for Burger King in India and Indonesia and Popeyes in Indonesia.
- The Indian Burger King business has reached a meaningful scale and is now showing better profitability.
Restaurant Brands Asia Ltd Complete Business Analysis
By Onetrader Guide
Introduction
Restaurant Brands Asia Ltd is one of the more interesting turnaround stories in India’s quick service restaurant sector. The company operates Burger King in India and Burger King and Popeyes in Indonesia. While the business has remained loss making at the consolidated level, its Indian operations have been steadily improving, creating a potentially interesting combination of store expansion, stronger margins and improving same store sales.
The company has also entered a new phase after Inspira Global completed its acquisition of control in July 2026. Inspira invested approximately Rs 2,235 crore and initially holds 41.78 percent of Restaurant Brands Asia, with its stake potentially increasing to 48.04 percent through additional capital infusion. The Burger King franchise agreements in India and Indonesia have also been extended until 2050, giving the company a much longer runway for expansion.
The important question now is whether Restaurant Brands Asia can convert Burger King’s growing Indian presence into sustainable consolidated profitability.
Also Read: Apollo Hospitals: How India’s Healthcare Giant Is Building Growth
Also Read: BlueStone Jewellery The Missed Gem?
Business Model
Restaurant Brands Asia operates as the master franchisee for Burger King in India and Indonesia and Popeyes in Indonesia. The company earns revenue from operating its restaurants while paying franchise related fees and royalties to Restaurant Brands International.
The business is primarily driven by restaurant sales, same store sales growth, new restaurant openings, average transaction value and restaurant level margins. Unlike a traditional retailer, QSR economics depend heavily on store productivity. A restaurant that generates strong sales from a relatively fixed cost base can produce attractive operating leverage.
India is currently the key part of the business. The company ended FY26 with 581 Burger King restaurants in India after adding 68 net stores during the year. India revenue increased 15.4 percent to approximately Rs 2,272 crore in FY26.
Also Read: Trent: How Westside and Zudio Are Driving Growth
Why India Is Becoming Interesting
The Indian Burger King business has reached a meaningful scale and is now showing better profitability.
India company EBITDA increased to approximately Rs 132 crore in FY26, compared with a much smaller contribution in FY22. Restaurant EBITDA margin improved to 11.6 percent from 5.2 percent over the same period.
This is important because store expansion alone does not guarantee value creation. Existing stores need to become more productive as well.
Aslo Read: Electronics Mart India: Can the Company Behind Bajaj Electronics Become a Powerhouse?
Management Strategy
Management’s strategy is focused on expanding the Burger King network while improving restaurant economics. The company has indicated an ambition to add around 60 to 80 restaurants annually, with FY26 already delivering 68 net additions. It is also targeting gross profit margins of around 70 percent by FY29.
Digital ordering, menu innovation, value offerings and customer experience remain important parts of the strategy. The company is also developing BK Cafe as an additional opportunity to increase customer frequency and improve utilisation of existing restaurant locations.
The biggest management development, however, is the change in ownership.
After Inspira Global completed its acquisition, Chairman Madhusudan Agrawal said the new promoter’s intention is to strengthen the existing business through patient capital, disciplined governance and a long term approach. Aayush Agrawal also highlighted operational excellence, customer focus and disciplined execution as priorities.
From an Onetrader perspective, the new ownership could become a meaningful catalyst if the additional capital is deployed toward profitable expansion rather than simply increasing store count.
Indonesia Is Still the Problem
The consolidated business cannot yet be judged only on India.
Restaurant Brands Asia operates 137 Burger King restaurants and 25 Popeyes restaurants in Indonesia. Burger King Indonesia moved slightly into positive restaurant EBITDA territory in FY26, but Popeyes remained significantly loss making.

This makes Indonesia the biggest drag on the consolidated business.
Burger King Indonesia could become a turnaround opportunity if store economics improve. Popeyes is more uncertain because the brand is operating from a much smaller base and has not yet demonstrated attractive economics.
For investors, the ideal scenario would be continued improvement in Burger King Indonesia while management remains disciplined about Popeyes expansion and capital allocation.
Also Read: What is a Dividend? Complete Guide for Indian Investors
Competitive Moat
Restaurant Brands Asia’s strongest competitive advantage is the Burger King brand.
The company also benefits from a large restaurant network, established supply chain infrastructure, digital capabilities and long term franchise agreements.
The extension of Burger King’s India and Indonesia franchise agreements until 2050 is particularly important because it provides long term visibility for the business.
However, the moat is not extraordinary. Restaurant Brands Asia competes with McDonald’s, KFC, Domino’s, Pizza Hut and numerous Indian QSR brands. Customers can easily switch between restaurants based on price, location and offers.
Therefore, execution and store economics remain more important than brand recognition alone.
Growth Drivers
India’s expanding middle class and increasing eating out frequency provide a structural opportunity for QSR companies. Organised restaurant chains can continue gaining market share as consumers increasingly prefer branded outlets for consistency, convenience and digital ordering.
Restaurant expansion remains another major growth driver. With 581 Burger King restaurants in India at FY26 end, there is still substantial room to increase the store network.
Same store sales growth could be even more important. Strong existing-store growth combined with new store additions can create a powerful revenue growth model.
Margin expansion is another potential catalyst. Management has already demonstrated significant improvement in India restaurant EBITDA margins, and further procurement, supply chain and operating efficiencies could improve profitability.
The new promoter’s capital infusion provides additional financial flexibility for the next phase of expansion.
Also Read: Zerodha Arbitrage Fund Explained: Returns, Taxation, Risks and Who Should Invest
Risks
The biggest risk is that consolidated profitability remains weak.
QSR businesses also face intense competition and customers are highly sensitive to pricing.
Food inflation can pressure gross margins, while rental and employee costs can affect restaurant profitability.
Rapid store expansion can also destroy value if new restaurants fail to reach mature productivity.
Indonesia remains a significant risk because Popeyes continues to generate losses.
The new promoter transition is another factor to monitor. Although the acquisition brings fresh capital and a long term stated strategy, investors will need several quarters of execution before judging its impact.
Investment Thesis
Restaurant Brands Asia is becoming more interesting because the investment thesis is gradually shifting from pure expansion to profitability.
The Indian Burger King business has reached meaningful scale, revenue is growing, restaurant margins have improved substantially and same store sales have started recovering.
The new promoter could provide fresh capital and a longer term approach.
The franchise agreements extending to 2050 remove a major long term uncertainty.
The key question is whether India can become strong enough to offset Indonesia and eventually generate sustainable consolidated free cash flow.
If that happens, the market could begin valuing Restaurant Brands Asia as a scalable consumer business rather than a loss making QSR expansion company.
Also Read: History of Crude Oil: From Ancient Civilizations to the Modern Oil Industry
Onetrader Verdict
Restaurant Brands Asia is an interesting turnaround plus growth story.
The Indian business is clearly the strongest part of the company, while Indonesia remains the key risk. The new Inspira Global ownership adds fresh capital and potentially a more patient approach to expansion.
For investors, the next few years should be about watching four things: same store sales growth, restaurant level margins, Indonesia losses and consolidated free cash flow.
If these indicators continue moving in the right direction, Restaurant Brands Asia could become one of the more interesting QSR stories in India’s consumption space.
India is the engine. Indonesia is the risk. The new promoter is the catalyst. Profitability is the test.
Rating
4 out of 5
Category: Quick Service Restaurants
Theme: Indian Consumption and QSR Turnaround
Disclaimer
This article is for educational and informational purposes only. It is not a buy or sell recommendation. Investors should independently evaluate the company’s financial statements, valuation, franchise agreements, debt, cash flows, competitive environment and future execution before making any investment decision.
Keep learning with OneTrader
Explore structured lessons and practical guides to build your market knowledge.

Need a laugh after all that money talk?
Paisa LOL: India's funniest finance page, with memes, comics, jokes and long funny stories.
