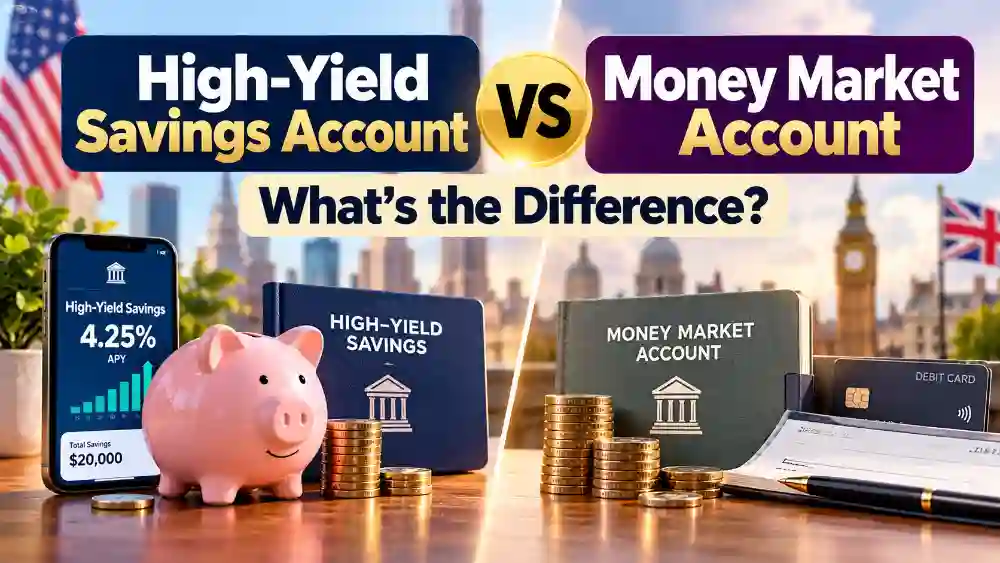
Choosing where to keep cash savings involves more than comparing advertised interest rates. In the United States, high-yield savings accounts (HYSAs) and money market accounts (MMAs) are popular deposit products for earning interest while maintaining access to funds. Both can accommodate emergency savings, short-term financial goals and money reserved for upcoming expenses.
Although these accounts share several characteristics, they differ in payment features, minimum balance requirements and account conditions. Understanding these differences helps explain how banks structure savings products and why the highest advertised annual percentage yield (APY) does not always produce the greatest net return.
What Is a High-Yield Savings Account?
A high-yield savings account is an interest-bearing deposit account that generally offers a higher APY than many conventional savings accounts. Online banks frequently provide these products, although traditional banks and credit unions may also offer competitive rates.
HYSAs are primarily designed for saving rather than everyday spending. Customers can typically transfer money electronically, arrange deposits and withdraw funds according to their institution’s account agreement.
Also Read: Certificate of Deposit (CD) vs Fixed-Rate Savings Bond: How Do They Work?
Most HYSAs have variable interest rates. Banks can adjust advertised APYs as market interest rates, funding requirements and competitive conditions change. Consequently, an advertised yield should not be interpreted as a guaranteed return over an entire year.
What Is a Money Market Account?
A money market account is an interest-bearing deposit account offered by banks and credit unions. It may combine savings account features with certain transaction capabilities associated with checking accounts.
Depending on the provider, an MMA may offer check-writing privileges, debit card access or ATM withdrawals. However, these features are not guaranteed, and some institutions impose transaction restrictions or additional account conditions.
Money market accounts may also offer tiered interest rates, where the applicable APY depends on the account balance. Some providers require minimum deposits or balances to qualify for particular rates or avoid monthly maintenance fees.
Also Read: Index Funds vs ETFs: Which Is Better for Long-Term Investing?
A money market deposit account should not be confused with a money market mutual fund. The latter is an investment product, not an insured bank deposit, and is not protected by FDIC deposit insurance.
How Do Interest Rates and APY Compare?
Neither HYSAs nor MMAs consistently offer higher interest rates. The difference depends on individual financial institutions, account conditions and market competition.
Consider a hypothetical $20,000 deposit earning 4.00% APY in an HYSA compared with 3.75% APY in an MMA. If both APYs remain unchanged for one year and the balances remain untouched, the accounts would earn approximately $800 and $750 respectively, before taxes and fees.
The resulting $50 difference illustrates how relatively small yield variations affect savings income. These rates are illustrative rather than verified current market offers.
Also Read: How Much Retirement Corpus Do You Need? A Complete Retirement Planning Guide
APY reflects the effect of compounding over a year, allowing depositors to compare interest earnings more consistently. However, fees, balance requirements and changes in variable rates can affect actual returns.
FDIC Insurance and Account Safety
Eligible HYSAs and MMAs at FDIC-insured banks receive the same federal deposit insurance protection.
The standard coverage limit is $250,000 per depositor, per insured bank, per ownership category. Deposits held in the same ownership category at one insured bank are combined when calculating coverage, regardless of whether the money is held in savings accounts, money market deposit accounts or certificates of deposit.
At federally insured credit unions, qualifying deposits receive protection through the National Credit Union Share Insurance Fund, administered by the National Credit Union Administration.
Also Read: How to Build a ₹1 Crore Corpus From Your Salary: A Practical Wealth-Building Plan
Deposit insurance protects eligible balances against qualifying institutional failures, not against inflation or the reduction of variable interest rates.
Withdrawal Limits and Access to Money
Access to savings is another important distinction between these account types. MMAs may offer checks or debit cards, while HYSAs typically emphasise electronic transfers.
On April 24, 2020, the Federal Reserve announced an amendment to Regulation D removing the federal six-per-month limit on convenient transfers from savings deposits. The change became effective that month.
However, banks are not required to permit unlimited withdrawals. Individual institutions may maintain transaction restrictions or impose fees under their account agreements.
Also Read: How to Choose a High-Yield Savings Account
Consequently, customers should examine transfer limits, ATM availability, processing times and potential charges rather than assuming that every savings account offers identical access.
Minimum Balances, Fees and Tax Treatment
Some HYSAs have no monthly maintenance fees or minimum balance requirements, while others impose conditions. MMAs may require larger balances to earn their highest advertised APYs or avoid charges.
There is no universal monthly maintenance fee or minimum deposit requirement applying to all US HYSAs or MMAs. These conditions depend on the provider.
Interest earned from either account is generally taxable for US federal income tax purposes. The IRS generally requires financial institutions to report qualifying interest payments of $10 or more on Form 1099-INT. Taxpayers must report taxable interest even when they do not receive the form.
Also Read: NPS for NRIs: Who Can Invest, Tax Benefits and Withdrawal Rules
For UK readers, comparable products include easy-access savings accounts and interest-bearing current accounts. For the 2026–27 tax year, the Personal Savings Allowance is £1,000 for basic-rate taxpayers, £500 for higher-rate taxpayers and £0 for additional-rate taxpayers. Qualifying Cash ISA interest remains tax-free under applicable ISA rules.
OneTrader Disclaimer: This article is provided for educational and informational purposes only and does not constitute financial, investment, tax or legal advice. OneTrader is not registered with SEBI or as an investment adviser with US or UK financial regulatory authorities. Interest rates, fees, account conditions, insurance eligibility and tax regulations may change. Readers should independently verify current requirements and consult qualified financial professionals when appropriate.
Keep learning with OneTrader
Explore structured lessons and practical guides to build your market knowledge.