Day 6 | 100 Days Money Mastery Series by OneTrader
Imagine applying for a personal loan to manage an unexpected expense. You have a stable job, a regular monthly salary and enough income to comfortably repay the EMI. Yet your loan application gets rejected. Meanwhile, someone earning less than you receives approval.
What could explain the difference? One possible reason is your credit score.
Many people believe their salary determines whether banks will lend them money. While income is important, lenders also want to understand how responsibly someone has handled borrowed money in the past. This is where your CIBIL Score becomes an important part of your financial identity.
Also Read: Why India’s Middle Class Is the Next Big Growth Engine
Understanding how credit scores work can help you avoid costly borrowing mistakes and make better financial decisions.
What Is a CIBIL Score?
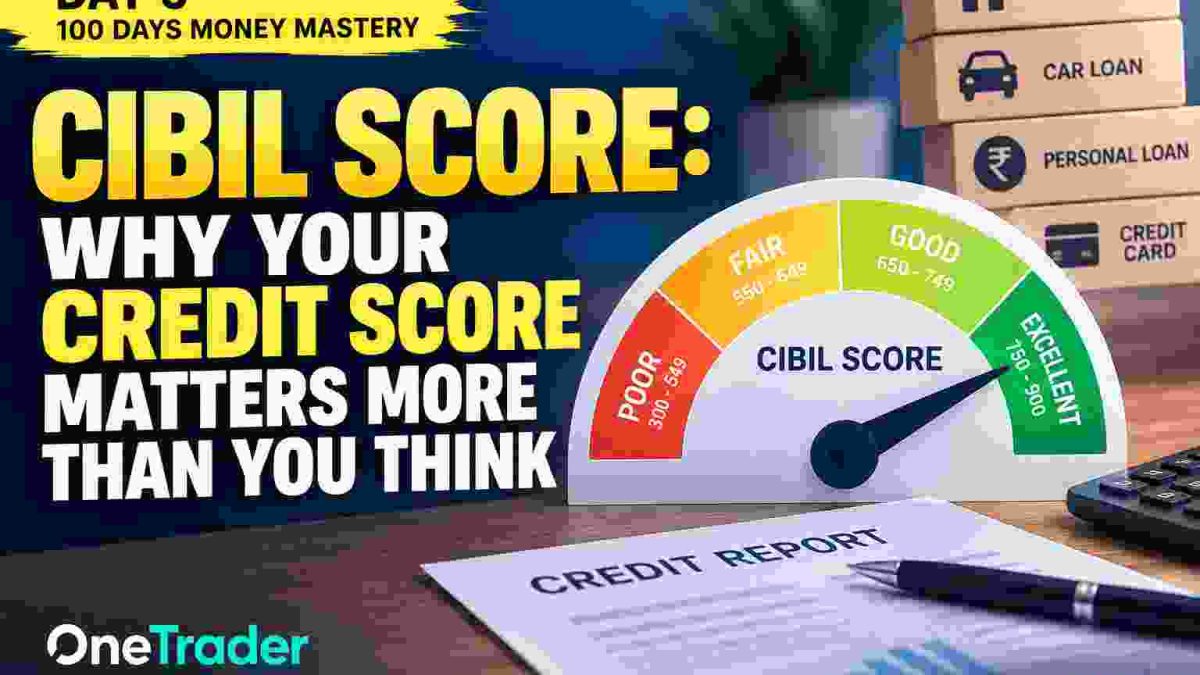
A CIBIL Score is a three-digit number ranging from 300 to 900, generated by TransUnion CIBIL using information from your credit history. It helps lenders assess your creditworthiness.
Your credit report contains details such as existing loans, credit-card accounts, outstanding balances, repayment history and credit enquiries.
Generally, a higher score indicates a stronger record of managing credit responsibly. A score of 750 or above is often considered favourable by lenders, although approval requirements differ between financial institutions.
Also Read: What Is a Mid-Cap Fund and Why Can It Offer Higher Growth Potential?
Importantly, a good score does not guarantee loan approval. Banks also evaluate your income, existing financial obligations, employment stability and internal lending policies.
Why Your Credit Score Can Affect the Cost of Borrowing
Consider two individuals applying for a ₹10 lakh personal loan over five years.
One applicant qualifies for an illustrative interest rate of 11% annually, while another is offered 15%. Their credit histories may be one factor behind the different offers, alongside income, employment and lender-specific criteria.
At 11%, the monthly EMI would be approximately ₹21,742. At 15%, it would be approximately ₹23,790.
Also Read: How to Buy and Sell ETFs in India – Complete Step-by-Step Guide for Beginners (2026)
That difference of roughly ₹2,048 every month translates into approximately ₹1.23 lakh in additional payments over five years.
This example demonstrates why maintaining a healthy credit profile matters. Your borrowing history can potentially influence not only whether you receive credit but also how expensive that credit becomes.
However, not every lender prices loans directly according to CIBIL Score, and rates should always be compared using actual offers.
The Biggest Factors That Influence Your CIBIL Score
Your repayment history is one of the most important elements of your credit profile. Missing credit-card payments or loan EMIs can damage your record, particularly when delays are reported to credit bureaus.
Also Read: US Stock Market Today: Nasdaq Slides as AI Selloff Deepens, Dow Gains
Credit utilisation is another important factor. Suppose your credit-card limit is ₹1 lakh and your reported outstanding balance is ₹85,000. That represents 85% utilisation, which may suggest heavy dependence on available credit.
Keeping reported balances relatively low can support healthier credit management. The commonly suggested 30% utilisation level is a guideline, not an official guarantee of a particular score.
Other considerations include the age of your credit accounts, the mix of credit products and recent applications for new borrowing.
Multiple loan or credit-card applications within a short period may generate several lender enquiries. These can influence how lenders assess your credit behaviour.
Also Read: US Stocks to Watch Today: TSMC, Nvidia, CoreWeave and Banks
Can You Have a Low Score Even With a High Salary?
Yes. Your credit score primarily reflects your credit history, not your salary.
Someone earning ₹1.5 lakh monthly could have a weak credit profile because of repeated late payments or excessive outstanding debt. Another person earning ₹35,000 could maintain a strong record by consistently repaying obligations on time.
A high salary does not automatically compensate for poor repayment habits.
Similarly, someone who has never borrowed money may have insufficient credit history rather than a bad credit score. Such individuals may receive an NA or NH designation instead of a conventional score.
Also Read: Top Gainers and Losers Today, 15 October 2026: 30 Indian Stocks in Focus
This is why financial discipline matters more than simply having a large income.
How to Improve Your CIBIL Score Over Time
Improving your credit profile usually requires consistent behaviour rather than quick tricks.
Start by paying every loan EMI and credit-card bill on time. Whenever possible, clear the total credit-card amount due instead of repeatedly carrying balances.
Review your credit report periodically to identify incorrect personal information, unfamiliar accounts or repayment entries that appear inaccurate. Errors should be disputed through the appropriate credit bureau and lender.
Also Read: Nifty Closing Today: Sensex Gains 875 Points, Nifty Ends at 22,881.90 on October 15
Avoid applying for unnecessary loans simply to increase your available borrowing capacity. If you already have expensive outstanding debt, prioritise a realistic repayment strategy.
You can also check your own credit report without treating that activity as a lender-initiated credit enquiry. In India, credit information companies must provide eligible individuals with one free full credit report, including the score, annually.
Most importantly, remember that genuine improvements may take time to appear because lenders report information periodically.
Your Credit Score Is Part of Your Financial Reputation
A credit score should not become an obsession or an excuse to borrow unnecessarily.
Also Read: Silver ETF vs Physical Silver: Which Is Better for Long-Term Investment?
You do not need multiple credit cards, personal loans or EMIs simply to demonstrate that you are financially responsible. Borrowing only when necessary and repaying consistently is a much healthier approach.
Your real financial strength comes from savings, manageable expenses, an emergency fund and sustainable debt levels. A healthy credit score complements those foundations.
The goal is not merely to achieve a high CIBIL Score. It is to build financial habits that make borrowing safer, more affordable and less stressful when you genuinely need it.
Financial Disclaimer
This article by OneTrader is for educational and informational purposes only. It does not constitute financial or investment advice, loan approval assurance, or a recommendation to purchase any financial product. Credit scores, interest rates and lending decisions vary by institution and individual circumstances. OneTrader is not a SEBI-registered investment adviser.
Also Read: AI in Manufacturing: Companies Benefiting From Industrial Automation
Keep learning with OneTrader
Explore structured lessons and practical guides to build your market knowledge.