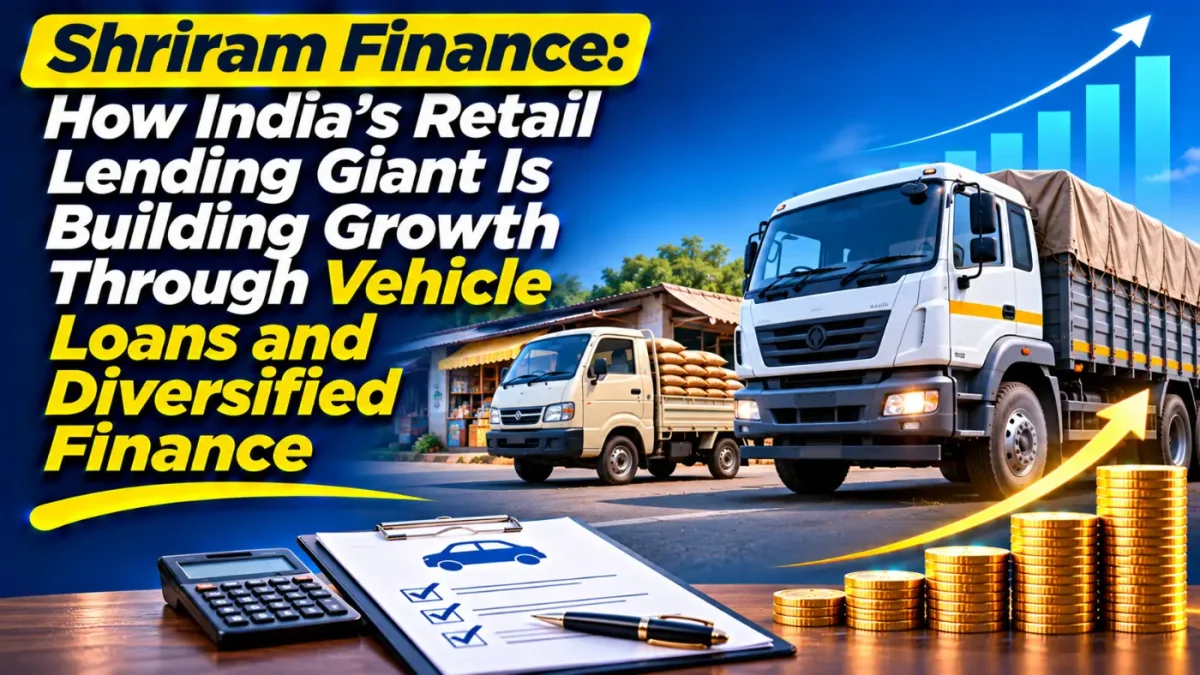
Shriram Finance is one of India’s largest retail-focused non-banking financial companies (NBFCs).
- India’s commercial transport and logistics sectors provide a major opportunity.
- Shriram Finance competes with banks, NBFCs and specialist lenders, including Mahindra Finance, Cholamandalam Investment and Finance, Bajaj Finance and banks offering vehicle and retail loans.
Shriram Finance is one of India’s largest retail-focused non-banking financial companies (NBFCs). It has built its business around financing commercial vehicles, used trucks, passenger vehicles, two-wheelers, construction equipment and small businesses.
The company serves customers who may have limited access to conventional bank credit, particularly small transport operators, self-employed individuals and rural borrowers. Its large branch network and experience in assessing borrowers with varied income profiles are important competitive strengths. Growth will depend on expanding its loan book while maintaining credit quality and controlling funding costs.
What Shriram Finance Does
Shriram Finance operates across several lending categories.
Commercial vehicle finance: Financing new and pre-owned trucks, buses and other commercial vehicles is a core business. It serves fleet operators, owner-drivers and small transport businesses. Its experience in used-vehicle financing is an important part of its market position.
Also Read: Apollo Hospitals: How India’s Healthcare Giant Is Building Growth
Passenger vehicle and two-wheeler finance: The company provides loans for cars, utility vehicles and two-wheelers, serving individual customers and households.
Construction equipment and tractor finance: It finances machinery and equipment used by contractors, infrastructure businesses, farmers and other operators.
Small business and MSME finance: Shriram Finance provides loans to small enterprises and self-employed customers for business requirements, working capital and asset purchases.
Personal and gold loans: Personal loans serve individual borrowing needs, while gold loans provide credit secured against pledged gold. These products diversify the loan portfolio beyond vehicle financing.
Also Read: Trent: How Westside and Zudio Are Driving Growth
Its operations are supported by a large branch network, rural centres, field employees and digital customer services.
Customers and How Shriram Finance Makes Money
Shriram Finance serves truck owners, fleet operators, small transport businesses, self-employed individuals, farmers, small manufacturers, traders and households. Many customers operate in the informal or semi-formal economy, where income documentation and conventional credit histories may be limited.

The company primarily earns interest income from loans. It raises funds through bank borrowings, market instruments, deposits and other funding arrangements, then lends to customers at rates that reflect borrower risk, loan duration and operating costs. The difference between interest earned and funding expenses forms a major part of its net interest income.
Fees and other lending-related income provide additional revenue. Loan processing, servicing and related charges contribute to earnings, while insurance distribution and other services can support customer relationships.
Vehicle finance remains a central part of the business. Used commercial vehicle lending requires knowledge of vehicle values, operating conditions, borrower cash flows and resale markets. This specialised underwriting experience helps Shriram Finance serve customers who may not fit conventional bank lending models.
Profitability depends on loan growth, interest spreads, funding costs, credit losses, collection efficiency and operating expenses. A growing loan book is valuable only when borrowers repay on time and the company earns adequate returns after accounting for defaults and provisions.
Growth Drivers
India’s commercial transport and logistics sectors provide a major opportunity. Demand for goods movement, infrastructure development and fleet replacement can support financing for trucks and other commercial vehicles. Shriram Finance’s experience in pre-owned vehicle lending gives it access to a specialised customer segment.
Passenger vehicle and two-wheeler financing can benefit from rising household incomes and credit demand beyond major cities. Its branch network allows the company to serve customers in smaller towns and semi-urban markets.
MSME and small-business lending offers another growth avenue. Small enterprises need financing for equipment, inventory and expansion, and many require lenders that understand their cash flows and business models.
Gold loans and personal loans broaden the product range and create additional customer relationships. However, growth in these segments must be balanced with prudent underwriting and collection standards.
The MUFG partnership strengthens the company’s capital base and could support access to funding, risk management expertise and future business opportunities. Technology investment and improved customer servicing may also help the company scale operations more efficiently.
Competition and Risks
Shriram Finance competes with banks, NBFCs and specialist lenders, including Mahindra Finance, Cholamandalam Investment and Finance, Bajaj Finance and banks offering vehicle and retail loans. Competition is particularly strong in passenger vehicle, personal and gold lending.
Credit risk is central to the business. Many borrowers operate small businesses or depend on transport and agricultural activity, where income can fluctuate. Weak economic conditions, poor monsoons or lower freight activity can affect repayment capacity.
Asset quality requires close monitoring. The increase in the gross Stage 3 ratio and the rise in gold loan delinquencies show why rapid portfolio growth must be accompanied by strong underwriting and collections.
Funding costs are another risk. NBFCs depend on banks and capital markets for a significant part of their borrowing. Higher interest rates or reduced market liquidity can compress lending spreads.
The company also faces regulatory requirements covering capital adequacy, provisioning, customer protection and lending practices. Competition, technology spending and expansion into newer loan categories may put pressure on operating costs.
What Investors Should Watch
AUM growth and loan disbursements indicate whether Shriram Finance is expanding its lending franchise. Investors should assess growth by product category rather than relying only on the consolidated number.
Asset quality is especially important. Gross and net Stage 3 ratios, collection efficiency, provisions and credit costs will show whether the company is maintaining discipline as it grows. Gold loan delinquencies and the performance of unsecured lending deserve particular attention.
Net interest income and net interest margins help explain how effectively the company is managing lending yields and funding costs. Investors should also track borrowing mix, cost of funds and the impact of changes in interest rates.
Capital adequacy, leverage and liquidity provide insight into financial resilience. The benefits of the MUFG investment should be assessed through lending growth, funding access and returns on the enlarged capital base.
Shriram Finance has a strong position in specialised retail lending, particularly commercial vehicle finance, supported by an extensive branch network and deep experience with small borrowers. Its expanding loan book and stronger capital position provide room for growth. Sustainable performance, however, will depend on credit discipline, asset quality and the ability to protect lending margins.
Financial Disclaimer: This article is for educational and informational purposes only. It is not investment advice or a recommendation to buy or sell any security. Investors should review company disclosures, financial statements, AUM growth, asset quality, credit costs, capital adequacy, funding risks and valuations and consult a qualified financial adviser before making investment decisions.
Keep learning with OneTrader
Explore structured lessons and practical guides to build your market knowledge.

Need a laugh after all that money talk?
Paisa LOL: India's funniest finance page, with memes, comics, jokes and long funny stories.