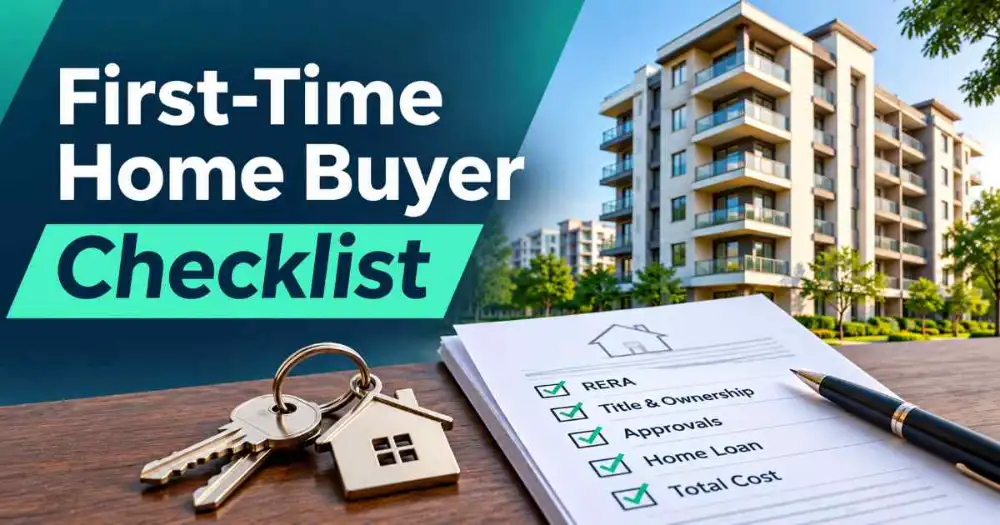
Buying a first home is a major financial milestone for most Indian families. It often involves years of savings, a substantial home loan and a long-term commitment to one location. The excitement of finding a suitable apartment or independent house can sometimes push buyers to make decisions before checking the legal documents, construction quality and actual cost of ownership.
A property that looks attractive in a brochure may have approval issues, unclear ownership or additional charges that significantly increase its purchase price. First-time buyers should approach the transaction with the same care they would give to any major financial decision. Understanding what to verify before paying the booking amount can prevent costly mistakes later.
1. Establish a Realistic Home Buying Budget
The first decision should be how much you can comfortably spend, rather than how much a bank is willing to lend. Lenders assess income, existing obligations, credit history and other factors to determine loan eligibility, but their calculation may not account for all your household expenses or future financial goals. A buyer earning ₹1.5 lakh per month, for example, may qualify for a substantial home loan but still find the resulting EMI uncomfortable after accounting for existing commitments, family expenses and investments.
Start by calculating your monthly disposable income after deducting regular expenses and existing EMIs. Consider how much you can allocate towards a home loan without depending on bonuses, uncertain salary increases or additional borrowing. Your budget should also leave room for emergency savings, insurance, retirement investments and unexpected household expenses. A home should provide financial stability rather than become a commitment that restricts every other financial decision.
Also Read: How to Check RERA Registration Before Buying a Property in India
The property price is only one part of the purchase cost. Stamp duty, registration, interiors, parking, maintenance deposits and loan-related expenses can increase the amount you need to arrange. Buyers should obtain a complete cost sheet from the builder or seller before deciding whether a property is affordable.
2. Choose a Location That Supports Your Daily Life
Location has a direct effect on the convenience and long-term usefulness of a home. A reasonably priced apartment in a developing suburb may appear attractive, but the decision becomes less appealing if commuting takes several hours every day or essential services are difficult to access. Examine the neighbourhood during working hours, evenings and weekends rather than relying on a single property visit.
For example, someone working in Hyderabad’s Financial District or Gachibowli may consider residential areas such as Tellapur, Nallagandla, Kondapur or Miyapur. Each location has different commuting patterns, infrastructure, property options and access to public transport. A buyer should compare the actual travel time to the workplace, availability of schools and hospitals, road conditions and everyday shopping facilities before selecting an apartment.
Water availability deserves particular attention in many Indian cities. Speak with existing residents about summer water supply, tanker dependency, drainage and flooding during the monsoon. Also examine whether promised roads, metro extensions or other infrastructure projects have received official approval rather than relying entirely on a builder’s sales presentation.
Also Read: Home Loan Basics in India: EMI, Interest Rate, Tenure and Eligibility Explained
3. Investigate the Builder or Seller’s Background
A builder’s reputation can tell you a great deal about how a project may be delivered and maintained. Before booking an apartment, examine the developer’s completed projects and speak with people who already live there. Their experience can reveal recurring problems such as possession delays, construction defects, poor maintenance, water shortages or disagreements over promised amenities.
Do not limit your investigation to online advertisements and customer testimonials published by the developer. Visit completed properties, examine the common areas and ask residents whether the actual facilities match what was promised during the sale. If the builder has completed several projects, look at the quality and maintenance of older developments as well.
For resale properties, the seller’s ownership and authority to sell require separate verification. If a property has multiple owners, inherited ownership or a Power of Attorney arrangement, the legal authority of everyone involved must be established before the transaction proceeds. A property lawyer can examine these documents and identify issues that may not be apparent during a normal site visit.
4. Verify RERA Registration and Project Details
The Real Estate (Regulation and Development) Act, 2016, brought greater transparency to India’s property market by establishing regulatory requirements for eligible real estate projects. Before purchasing an under-construction apartment, check the project’s registration on the relevant state RERA website. In Telangana, buyers can use the Telangana RERA portal to examine registered projects and promoter information.
The registration number should correspond to the exact project and phase being advertised. Compare the registered project address, developer details, approved plans, apartment specifications and declared completion date with the information provided by the sales team. Pay attention to revised completion timelines, project extensions and regulatory orders because these can affect when you receive possession.
RERA registration should not be treated as a guarantee that every aspect of the property is legally clear. Buyers must independently verify land ownership, building permissions, financial obligations and other relevant documents. For a resale apartment, examine the project’s registration history and the requirements applicable to the particular transaction.
5. Examine the Property’s Title and Ownership Documents
Legal ownership is one of the most consequential aspects of a property purchase. Before paying a substantial amount, establish whether the seller has a valid and transferable title to the land or apartment. An independent property lawyer should examine the ownership history rather than relying only on photocopies supplied by the builder or seller.
The lawyer should review the registered sale deed, previous title deeds and mother deed, where applicable, to understand how ownership has passed from one party to another. An Encumbrance Certificate can help identify registered transactions and encumbrances recorded against the property during the period examined. However, it does not establish that the property is completely free from every possible claim, dispute or unregistered interest.
The verification should also cover outstanding mortgages, pending court cases, inheritance claims, acquisition proceedings and restrictions on transferring the property. Where the property has changed hands through inheritance, partition or a gift, the corresponding documents must be examined. Buyers should also verify relevant land records and municipal records with the competent authorities.
A clean-looking document file is not enough if the underlying ownership history contains gaps. Legal verification should be completed before executing the sale agreement or making a significant payment.
6. Check Building Approvals and Government Permissions
A property can have an attractive design and modern facilities while still having construction or approval irregularities. Buyers should verify whether the building has been developed according to the permissions granted by the competent planning and municipal authorities. The documents required will depend on the property’s location, type and stage of construction.

For an apartment project, examine the sanctioned building plan and building permission. Compare the approved number of floors, apartment layouts and permitted construction with what is actually being built. If the project involves multiple phases or towers, confirm that the approvals and registration cover the specific apartment being purchased.
Other permissions may include environmental clearance, fire safety approval and specialised clearances depending on the size, location and nature of the development. For completed buildings, examine the Completion Certificate and Occupancy Certificate wherever applicable. An Occupancy Certificate is particularly relevant because it indicates that the competent authority has permitted occupation after considering the applicable requirements.
Do not assume that electricity connections, water connections or possession letters automatically establish building compliance. If the developer has made additional construction beyond the sanctioned plan, ask your lawyer to assess its implications before proceeding.
7. Understand the Agreement for Sale Before Signing
The agreement for sale establishes the commercial and contractual terms of the transaction. Buyers sometimes concentrate on the apartment price and possession date while overlooking clauses that govern delays, cancellations, additional charges and changes to specifications. These provisions can have a substantial financial impact if the project does not proceed as expected.
Read the agreement alongside the builder’s payment schedule, approved plans and RERA disclosures. The apartment identification, carpet area, total consideration, promised specifications and possession terms should match the information communicated during the purchase process. If the agreement permits changes to the layout, amenities or construction specifications, understand the conditions under which those changes can be made.
Pay particular attention to cancellation provisions, refund timelines and compensation for delayed possession. Examine how parking, maintenance deposits, club facilities and other charges are treated. Any significant promise made by the builder should be reflected in the contractual documents rather than left as a verbal assurance.
Have an independent property lawyer review the agreement before signing. This is especially useful when the document contains lengthy conditions or provisions that appear to give the developer broad discretion.
8. Understand Carpet Area Before Comparing Apartments
Indian property advertisements frequently use carpet area, built-up area and super built-up area to describe apartment sizes. These terms are not interchangeable, and comparing properties using different area measurements can produce misleading conclusions. A larger advertised apartment does not necessarily offer more usable living space.
Under RERA, carpet area refers to the net usable floor area of an apartment, excluding external walls, service shafts, exclusive balcony or verandah areas and exclusive open terrace areas, while including the area covered by internal partition walls. Built-up area generally includes the carpet area along with walls and other included structural elements. Super built-up area may additionally include an allocated share of common spaces such as corridors, lobbies and other shared facilities.
Consider two apartments advertised at the same super built-up area. One may offer a larger carpet area because its layout uses space more efficiently, while the other may have relatively larger common-area loading. The difference becomes meaningful when you compare the actual living room, bedrooms, kitchen and usable circulation space.
Always ask the builder for the RERA carpet area and examine the floor plan. Visit a sample apartment or a completed unit to understand whether the advertised dimensions translate into comfortable living space.
9. Assess Home Loan Eligibility and EMI Affordability
Most first-time home buyers depend on housing finance to complete their purchase. Before committing to a property, approach multiple banks or housing finance companies and understand the loan amount, interest rate, tenure and associated conditions. A lender’s preliminary eligibility estimate is useful, but final approval also depends on property valuation, documentation and legal assessment.
For example, consider a buyer taking a home loan of ₹60 lakh at an illustrative annual interest rate of 8.5% for 20 years. The approximate EMI would be ₹52,100 per month. Extending the tenure may reduce the monthly instalment, but it also increases the total interest paid over the life of the loan.
| Particulars | Illustrative amount |
|---|---|
| Home loan | ₹60,00,000 |
| Annual interest rate | 8.5% |
| Loan tenure | 20 years |
| Approximate monthly EMI | ₹52,100 |
| Approximate total repayment | ₹1.25 crore |
| Approximate total interest | ₹65 lakh |
The calculation assumes a constant interest rate throughout the loan period and regular monthly repayments. Actual EMI and total interest can change when floating interest rates are revised or repayment conditions differ.
Compare lenders on more than the starting interest rate. Examine the benchmark, spread, reset frequency, processing charges and prepayment conditions. Also understand whether the lender will release the loan amount in stages for an under-construction property and how that affects your repayment obligations.
10. Inspect Construction Quality and Physical Condition
A property inspection should go beyond checking the apartment’s appearance. For a ready-to-move home, examine walls, ceilings, bathrooms, plumbing, electrical fittings, ventilation and windows. Water seepage around bathrooms and external walls can indicate waterproofing problems that may become expensive after possession.
In apartment buildings, common facilities deserve equal attention. Check the condition of lifts, staircases, parking areas, fire safety systems, water storage, electrical backup and drainage arrangements. Speak with existing residents about maintenance quality and recurring repair expenses. A well-maintained apartment complex can offer a very different ownership experience from a building where basic facilities are frequently unavailable.
For an under-construction apartment, compare the construction with the specifications mentioned in the agreement and approved plans. Visit the site at different stages if possible and examine the materials and workmanship. An independent inspection professional can help identify defects that an ordinary buyer may overlook.
11. Understand Maintenance Costs and Apartment Association Rules
The financial responsibility of owning an apartment does not end after registration. Monthly maintenance charges generally cover security, housekeeping, lifts, common electricity, water systems, landscaping and other shared facilities. Larger residential communities may also collect additional amounts for repairs, equipment replacement or building maintenance reserves.
Ask the developer or apartment association how maintenance is calculated and whether charges are based on apartment size, a fixed amount or another agreed arrangement. For resale properties, examine the association’s financial records and confirm that the seller has cleared outstanding maintenance payments. An apartment with attractive facilities may carry substantial recurring expenses that should be included in your household budget.
Read the association’s rules before purchasing, particularly if you intend to rent the apartment in the future. Understand the provisions relating to parking, pets, renovations, visitors and use of common facilities. These rules can influence your experience as an owner and the practical use of the property.
12. Calculate the Complete Purchase Cost
The advertised property price rarely represents the final amount required to own a home. Buyers must account for government charges, applicable taxes, interiors and other transaction-related expenses. These additional costs should be calculated before arranging the down payment or signing the agreement.
Consider an illustrative purchase of an under-construction residential apartment priced at ₹75 lakh. Assuming the applicable GST rate is 5%, the tax alone would add ₹3.75 lakh to the basic price. Interiors, furnishing and other initial expenses can increase the overall requirement further.
| Particulars | Illustrative amount |
|---|---|
| Basic apartment price | ₹75,00,000 |
| GST at assumed 5% | ₹3,75,000 |
| Interior and furnishing | ₹4,00,000 |
| Other initial expenses | ₹1,50,000 |
| Total before stamp duty and registration | ₹84,25,000 |
This example assumes a transaction where the 5% residential construction GST rate applies. Affordable residential housing may qualify for a different rate, subject to prescribed conditions. GST generally does not apply to the sale of a completed property where the entire consideration is received after the applicable completion certificate or first occupation, whichever is earlier.
Stamp duty and registration charges are separate government expenses and vary across states. Buyers in Telangana, Maharashtra, Karnataka and other states should calculate these charges using the applicable state rules rather than relying on estimates from another city. Obtain a written breakup of every payment before transferring money to the seller or builder.
13. Understand TDS and Other Tax Responsibilities
Property transactions can involve tax compliance responsibilities for buyers, particularly when the transaction value is substantial. Under Section 194-IA of the Income-tax Act, 1961, a buyer purchasing qualifying immovable property from a resident seller generally has to deduct TDS at 1% when the consideration or stamp duty value, whichever is higher, is ₹50 lakh or more. The provision does not apply to agricultural land as defined under the applicable law, and purchases from non-resident sellers fall under different TDS provisions.
For example, if a qualifying property has a purchase consideration of ₹80 lakh and the seller is a resident, the buyer generally has to deduct ₹80,000 as TDS. The buyer must follow the prescribed payment and reporting process, including filing Form 26QB and issuing the applicable TDS certificate. The Income Tax Department also specifies that incidental charges forming part of the property consideration are covered under the relevant provisions. <Cite refs={[“turn545700search0″,”turn545700search14”]}/>
Home loan tax benefits may also be relevant depending on the property, ownership structure, loan purpose and income-tax regime selected. Buyers should not assume that every home loan automatically produces the same tax savings. A chartered accountant can assess the applicable deductions and reporting requirements before the purchase is completed.
14. Complete Registration and Take Possession
Once the legal checks, agreement and financing arrangements are complete, the sale deed must be executed and registered with the appropriate Sub-Registrar. Verify that the document correctly identifies the property, buyer, seller, consideration and other agreed terms. Ensure that all applicable stamp duty and registration requirements are fulfilled and obtain the registered document after the process is completed.
Possession should be treated as a separate stage of verification rather than a routine handover. For a completed apartment, examine the Occupancy Certificate where applicable, possession letter, utility connections and other relevant project documents. Check the apartment physically and record any pending repairs or defects in writing before signing the final handover acknowledgement.
After taking possession, complete the applicable municipal and utility ownership-transfer procedures. Keep the registered sale deed, loan documents, payment receipts, tax records and association documents safely. These records may be required later for resale, inheritance, refinancing or resolving ownership-related questions.
Common Mistakes That Can Cost First-Time Buyers Money
One frequent mistake is making a booking payment because a sales representative claims that only a few apartments remain available. Buyers should resist such pressure until they have examined the property’s basic legal and financial details. A short-term promotional offer is rarely worth taking an unnecessary legal or financial risk.
Another mistake is calculating affordability using only the monthly EMI. Homeownership brings recurring maintenance costs, property taxes, repairs, insurance and other expenses that continue even after the loan repayment begins. Buyers who use all their available savings for the down payment may find themselves borrowing again when an unexpected expense arises.
Some buyers also assume that bank loan approval means the property has been fully verified. A lender conducts checks for its own lending decision, but the buyer remains responsible for understanding the ownership, contractual terms and practical suitability of the property. Independent legal advice and a physical inspection should remain part of the purchase process.
Finally, avoid selecting a property entirely because of its expected appreciation. Future prices depend on infrastructure, demand, supply, economic conditions and several other factors. A first home should primarily meet your housing needs and remain affordable over the long term.
Final Thoughts
Buying your first home in India requires patience, financial discipline and careful verification. A property may look perfect during a sales visit, but the real quality of the purchase depends on its legal ownership, government approvals, construction standards and total cost.
Start with a budget that leaves enough room for your other financial responsibilities. Compare locations, investigate the builder, examine the title documents and understand the agreement before making a substantial payment. Take independent legal and financial advice wherever necessary rather than relying entirely on the seller’s assurances.
The right home is not necessarily the most expensive apartment or the one with the longest list of amenities. It is a property that you can legally own, comfortably afford and live in without putting unnecessary pressure on your family’s finances.
Disclaimer: This article is for educational purposes only and does not constitute investment, legal or tax advice. Consult qualified professionals before making property-related decisions.
Keep learning with OneTrader
Explore structured lessons and practical guides to build your market knowledge.

Need a laugh after all that money talk?
Paisa LOL: India's funniest finance page, with memes, comics, jokes and long funny stories.