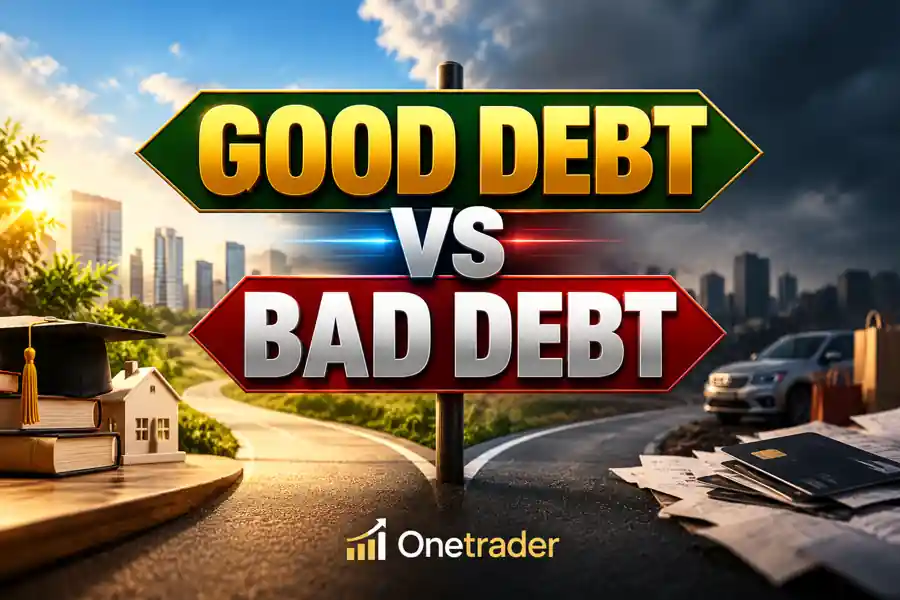
Debt is one of the most misunderstood aspects of personal finance. Some people believe all borrowing is dangerous, while others use loans and credit cards without considering their long-term consequences. In reality, debt can help finance education, acquire valuable assets, or expand a business. It can also drain savings, increase financial stress, and delay wealth creation. Understanding good debt versus bad debt means evaluating why you borrow, what it costs, and whether it improves your financial future.
What Is Good Debt?
Good debt generally refers to borrowing that has reasonable potential to create long-term financial value. It may support higher earning capacity, productive business activity, or the acquisition of an asset. However, no loan automatically qualifies as good debt simply because it finances education, property, or business expansion.
For example, an education loan may be worthwhile when the qualification significantly improves career prospects and expected earnings justify repayment costs. Similarly, financing equipment that increases business productivity may generate additional income. The crucial consideration is whether realistic benefits outweigh interest expenses, repayment obligations, and financial risks.
What Is Bad Debt?
Bad debt typically finances consumption without creating sufficient lasting financial value, especially when borrowing costs are high. Revolving credit card balances, unnecessary personal loans, and expensive lifestyle purchases can gradually weaken financial stability.
Also Read: Trading Discipline: The Key to Better Decision-Making in the Stock Market
Consider someone regularly buying electronics, furniture, and luxury products through instalment plans. Individual payments may appear manageable, but overlapping obligations can consume a substantial portion of monthly income. Consequently, less money remains for emergencies, investments, and essential expenses. The situation becomes particularly dangerous when new borrowing is required to repay existing debt.
Why Interest Rates Matter More Than Monthly EMIs
Borrowers frequently judge affordability through monthly instalments rather than total repayment costs. Longer loan tenures reduce monthly payments but usually increase the overall interest burden.
Consider a ₹5 lakh loan carrying 12% annual interest on a monthly reducing balance, excluding fees. A three-year tenure produces an approximate monthly EMI of ₹16,607 and total interest of ₹97,900. Extending repayment to five years reduces the EMI to approximately ₹11,122 but increases total interest to ₹1.67 lakh. The lower monthly payment creates breathing room, yet costs roughly ₹69,000 more in interest. Compare effective borrowing costs, processing fees, tenure, and total repayments before choosing a loan.
Is a Home Loan Good Debt or Bad Debt?
Home loans are commonly considered good debt because property may appreciate over time. However, purchasing property also involves interest, maintenance, taxes, insurance, and transaction expenses. Appreciation is uncertain, and real estate cannot always be sold quickly.
Also Read: Emergency Fund: How Much Money Should You Really Keep in Cash?
A reasonably priced home that meets long-term housing needs may be financially sensible when repayments leave adequate room for savings and emergencies. Conversely, an oversized mortgage can restrict financial flexibility for decades. Evaluate affordability, employment stability, alternative housing costs, and realistic property expectations rather than assuming ownership always guarantees wealth creation.
How Debt Affects Wealth Creation
Every loan repayment reduces the income available for saving and investing. High-interest debt is particularly damaging because borrowing costs can exceed achievable investment returns.
Suppose a credit card balance attracts 30% annual interest while an investment portfolio might earn 10%, without any guarantee. Continuing to carry expensive revolving debt while aggressively investing may undermine overall financial progress. Paying down that balance provides a predictable reduction in interest expenses, whereas market returns remain uncertain. For many households, eliminating costly debt is therefore more valuable than chasing higher investment returns.
When Borrowing Becomes a Financial Trap
Debt becomes risky when repayments depend on optimistic assumptions about future income or asset prices. Salary increases may be delayed, businesses may experience weak demand, and property values may stagnate. Yet lenders generally expect scheduled repayments regardless of these developments.
Also Read: Assets vs Liabilities: The Financial Lesson That Can Change Your Life
Borrowers should consider whether they could manage essential expenses and loan payments during temporary income disruption. Emergency savings and manageable repayment commitments provide important protection. Borrowing to speculate in stocks or other volatile assets deserves particular caution because investment losses can occur while repayment obligations remain unchanged.
How to Make Smarter Borrowing Decisions
Before borrowing, assess whether the purchase is necessary, whether it creates meaningful value, and whether repayments remain affordable under less favourable circumstances. Compare lenders using total borrowing costs rather than promotional rates or attractive EMIs.
If you already carry multiple debts, prioritising high-interest balances can reduce unnecessary interest expenses. Avoid relying indefinitely on minimum credit card payments, which can prolong repayment. Maintain an appropriate emergency reserve alongside your repayment plan to reduce the likelihood of borrowing again when unexpected expenses arise.
Final Thoughts
Good debt and bad debt are not fixed labels attached to particular financial products. Their real impact depends on purpose, affordability, interest costs, risk, and financial outcomes. Even productive borrowing can become harmful when excessive, while carefully planned financing may support long-term opportunities.
Also Read: NPS for NRIs: Who Can Invest, Tax Benefits and Withdrawal Rules
Onetrader Insight: Financial strength is not measured by borrowing capacity or expensive possessions. It comes from building valuable assets, maintaining manageable obligations, and preserving financial flexibility. Borrow only when the expected benefits justify the costs and risks.
Financial Disclaimer: This article is for educational and informational purposes only. It does not constitute financial or investment advice or a recommendation to buy or sell any financial product. Borrowing and investing involve risks, and decisions should reflect individual financial circumstances. Onetrader is not SEBI registered.
More useful tools from OurPaisa
Explore calculators, everyday tools and practical resources.