Most household budgets account for rent, groceries, utilities and monthly debt payments. The trouble often comes from expenses that do not arrive every month. Car insurance renewals, property taxes, school fees, Christmas shopping and home repairs can put pressure on a budget even when the costs were predictable.
A sinking fund offers a practical way to manage these bills. Instead of finding the entire amount when payment is due, households gradually set aside money throughout the year.
For families in the United States and United Kingdom, sinking funds can make irregular expenses easier to manage without treating every large bill as a financial emergency.
What Is a Sinking Fund?
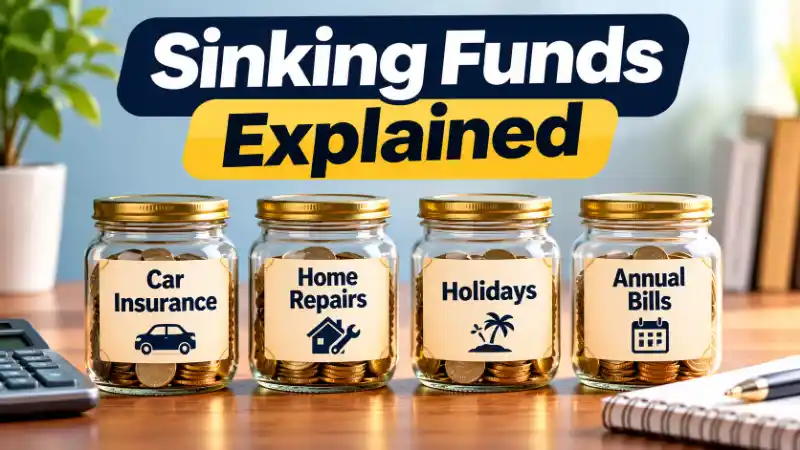
A sinking fund is money reserved for a specific future expense. The expense may have a known payment date, such as an annual insurance renewal, or an estimated timeframe, such as replacing a household appliance.
Also Read: High-Yield Savings Account vs Money Market Account: What’s the Difference?
Unlike general savings, each sinking fund has a defined purpose. Money allocated to vehicle maintenance is kept separate from savings intended for holidays or property repairs.
The concept originally comes from arrangements used to accumulate money for future financial obligations. In household budgeting, it simply means spreading an anticipated cost across several pay periods.
A sinking fund does not require a specialised banking product. Households can use separate savings accounts, budgeting applications or labelled savings categories within an existing account.
How Much Should You Save in a Sinking Fund?
The calculation begins with the expected expense and the time remaining before payment. Dividing the estimated cost by the number of months available gives a monthly savings target.
Also Read: Certificate of Deposit (CD) vs Fixed-Rate Savings Bond: How Do They Work?
Consider these illustrative household expenses.
| Expense | Expected cost | Months available | Monthly saving |
|---|---|---|---|
| US car insurance | $1,200 | 12 | $100 |
| US home maintenance | $2,400 | 12 | $200 |
| UK Christmas spending | £600 | 12 | £50 |
| UK annual car expenses | £900 | 9 | £100 |
These figures are hypothetical budgeting examples, not current market prices or national spending averages. The calculations assume equal monthly contributions, with no interest earnings, withdrawals or account fees.
Actual savings targets depend on household circumstances, expected price changes and payment deadlines. When an expense is uncertain, reviewing previous bills can provide a more realistic estimate.
Sinking Fund vs Emergency Fund
The main difference between a sinking fund and an emergency fund is whether an expense can reasonably be anticipated.
Also Read: How Much Retirement Corpus Do You Need? A Complete Retirement Planning Guide
An annual insurance renewal is predictable, even when the final premium changes. A sudden loss of income or an unexpected major repair is different.
Using emergency savings for routine annual bills can gradually weaken a household’s financial reserve. Sinking funds help separate planned obligations from genuinely unexpected expenses.
Some costs fall between these categories. Routine vehicle servicing is predictable, while an unexpected engine failure may not be. A household might maintain a vehicle maintenance fund while recognising that unusually expensive repairs could require additional savings.
Where Should You Keep Sinking Fund Savings?
Because sinking funds are intended for future spending, accessibility matters. Ordinary savings accounts that allow withdrawals when bills become due are commonly used.
Also Read: How to Build a ₹1 Crore Corpus From Your Salary: A Practical Wealth-Building Plan
In the United States, eligible deposits at FDIC-insured banks receive protection of up to $250,000 per depositor, per insured bank, per ownership category. Multiple accounts held in the same ownership category at one bank are combined when calculating coverage.
In the United Kingdom, eligible deposits at authorised banks, building societies and credit unions receive FSCS protection of up to £120,000 per eligible person, per authorised firm. This limit took effect on December 1, 2025.
Savings pots within the same bank do not automatically receive separate deposit protection limits.
Withdrawal restrictions, minimum balance requirements and account fees depend on the provider. These conditions matter when money is being reserved for a bill with a fixed payment deadline.
Also Read: How to Choose a High-Yield Savings Account
Are Sinking Funds Taxable?
Creating a sinking fund does not itself trigger income tax. Moving money between personal savings accounts generally does not create taxable income.
However, interest earned on the money may be taxable.
In the United States, interest earned from ordinary bank savings accounts is generally subject to federal income tax. Taxable interest must be reported even when the account holder does not receive Form 1099-INT.
In the United Kingdom, savings interest outside tax-exempt accounts may be taxable depending on total income and available allowances.
Also Read: NPS for NRIs: Who Can Invest, Tax Benefits and Withdrawal Rules
For the 2026–27 tax year, the Personal Savings Allowance is £1,000 for basic-rate taxpayers, £500 for higher-rate taxpayers and £0 for additional-rate taxpayers. Other tax-free allowances may apply depending on individual circumstances.
Qualifying interest earned within a Cash ISA is generally exempt from UK income tax. However, a sinking fund is a budgeting method, not a separate tax-advantaged account.
Common Sinking Fund Mistakes
One common mistake is underestimating future expenses. Insurance premiums, travel costs and repairs may increase before the payment deadline, leaving households with less money than expected.
Another problem is creating too many savings categories without considering available income. A household may identify numerous future obligations but struggle to fund them alongside essential monthly expenses.
Also Read: Why You Should Pay Yourself First | Smart Money Habit Explained – Onetrader
Savings targets also need occasional adjustment. Changes in income, cancelled purchases or revised payment dates can make an earlier budget unrealistic.
Why Sinking Funds Make Budgeting More Predictable
A sinking fund does not reduce the actual cost of a bill. What it changes is when the household sets aside the money.
Rather than paying a large annual expense entirely from one month’s income, the cost is spread across several pay periods. This can reduce dependence on short-term borrowing and make household cash flow easier to manage.
For American and British households alike, the principle is straightforward. A bill that arrives once a year is still part of the cost of living throughout the year. Recognising that expense before the payment deadline makes it easier to prepare.
Also Read: Where is Indian Investors’ Wealth? Gold, Real Estate, or Markets?
OneTrader Disclaimer: This article is provided for educational and informational purposes only and does not constitute financial, investment, tax or legal advice. It is not a recommendation to buy or sell any financial product. OneTrader is not registered with SEBI or as an investment adviser with US or UK financial regulatory authorities. Savings account terms, interest rates, deposit protection eligibility and tax regulations may change. Readers should verify applicable requirements and consult qualified financial professionals where appropriate.
Keep learning with OneTrader
Explore structured lessons and practical guides to build your market knowledge.
Need a laugh after all that money talk?
Paisa LOL: India's funniest finance page, with memes, comics, jokes and long funny stories.