An exchange-traded fund can earn money from more than dividends, bond interest and changes in the value of its investments. Some ETFs also generate revenue by temporarily lending securities from their portfolios to other market participants. The practice, known as securities lending, operates largely out of sight of ordinary investors, yet it can influence a fund’s performance and introduce risks that deserve attention.
Securities lending is used by investment funds in both the United States and United Kingdom. It is particularly relevant to ETFs holding large portfolios of shares that are in demand among institutional borrowers. While the income can help offset fund expenses, the arrangements differ considerably between providers.
What Is Securities Lending in an ETF?
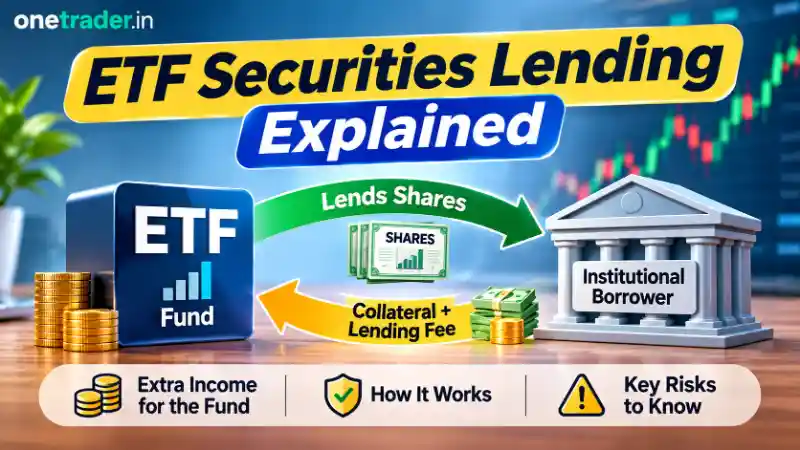
Securities lending allows an ETF to temporarily transfer shares or other eligible securities to an approved borrower in exchange for collateral and a lending fee.
Borrowers are typically financial institutions such as broker-dealers and investment banks. They may need securities to facilitate short selling, settle transactions or support other market activities.
Also Read: Top 10 ETFs in India by Assets Under Management (AUM)
The ETF remains economically exposed to the securities it lends and is entitled to receive equivalent securities when the loan ends. However, legal ownership generally transfers to the borrower during the lending period.
This distinction matters because securities lending is not the same as selling an investment. The fund continues pursuing its investment strategy while earning additional income from the lending arrangement.
How Securities Lending Generates Revenue
The economics of securities lending depend on demand for particular securities, borrowing conditions and the collateral provided.
When a borrower provides noncash collateral, such as government securities, the borrower typically pays a lending fee. Cash collateral arrangements can work differently, with revenue potentially generated by investing the collateral and paying the borrower an agreed rebate.
Also Read: Gold ETF vs Physical Gold: Key Differences, Costs, Benefits and Risks
Consider a hypothetical ETF that lends $20 million worth of securities at an average annual lending fee of 0.30%. If those securities remain on loan for an entire year, gross lending revenue would be approximately $60,000.
| Lending example | Figure |
|---|---|
| Securities on loan | $20 million |
| Average annual lending fee | 0.30% |
| Gross lending revenue over one year | About $60,000 |
That amount is not necessarily the income retained by the ETF. Lending agents, operational arrangements and revenue-sharing agreements can affect the final amount credited to the fund.
The revenue also changes as securities demand and borrowing rates fluctuate.
Why ETF Providers Participate in Securities Lending
For fund managers, securities lending offers an additional source of portfolio income without requiring a fundamental change to the ETF’s investment objective.
Also Read: How to Buy and Sell ETFs in India – Complete Step-by-Step Guide for Beginners (2026)
A fund tracking a broad equity benchmark may hold hundreds or thousands of securities. Some holdings may attract borrowing demand, creating opportunities to earn fees.
The resulting income can help offset operating expenses and potentially improve the fund’s performance relative to its benchmark.
However, securities lending revenue is neither guaranteed nor consistent. A fund may earn relatively little during periods of weak borrowing demand, while particular securities can command higher fees when they become difficult to borrow.
Investors should therefore avoid treating lending income as a predictable dividend or fixed return.
Also Read: Accumulating vs Distributing ETFs: How They Work and How Dividends Are Taxed
What Happens if a Borrower Fails to Return Securities?
The central risk in securities lending is that a borrower may fail to return the securities as agreed.
ETF lending programmes generally require borrowers to provide collateral, often worth more than the securities being borrowed. Collateral values are monitored and adjusted as market prices change.
Nevertheless, collateral does not eliminate every possible loss. If a borrower defaults during a sharp market movement, the value of the collateral may be insufficient to replace the securities.
Cash collateral can introduce another risk when it is reinvested. Losses on those investments may affect the lending programme’s financial results.
Also Read: How to Start Investing in ETFs in India
Some providers arrange additional protections against borrower default, but their terms and coverage vary.
Securities Lending Rules in the US and UK
In the United States, ETFs participating in securities lending operate under applicable investment company regulations and regulatory guidance. Fund disclosures explain the lending programme, associated risks and arrangements for collateral.
UK investors commonly encounter securities lending within UCITS ETFs. Applicable fund rules require safeguards covering collateral, risk management and the treatment of lending revenue.
For investors using a Stocks and Shares ISA, SIPP, Roth IRA or 401(k), securities lending conducted inside an ETF is distinct from an individual brokerage account lending out the investor’s ETF shares.
Also Read: Best ETFs to Buy in India for Long-Term Investment
The two arrangements have different contractual relationships and should not be confused.
How Investors Can Check an ETF’s Lending Policy
ETF providers generally explain their securities lending arrangements in prospectuses, annual reports and other fund documents.
These disclosures may identify the proportion of assets available for lending, collateral requirements, revenue-sharing arrangements and historical lending income.
Investors comparing similar funds can examine how much lending revenue remains with the ETF after programme costs.
Also Read: How to Select the Right ETF – Step-by-Step Guide for Indian Investors (2026)
A fund retaining a larger share of lending income may benefit shareholders, although the quality of its risk controls remains equally important.
Securities lending is one of the less visible activities behind ETF management. Understanding how it works provides a clearer picture of how funds operate beyond their published holdings and benchmark returns.
OneTrader Disclaimer
This article is published by OneTrader for educational and informational purposes only. It does not constitute financial, investment, tax or legal advice, or a recommendation to buy or sell any security. OneTrader is not registered with SEBI and is not acting as an SEC-registered investment adviser or FCA-authorised financial adviser. Investments involve risk, including possible loss of capital. Readers should conduct independent research and consult appropriately qualified professionals before making investment decisions.
Also Read: ETF vs Sukanya Samriddhi Yojana (2025) — Which Is Better for You?
Keep learning with OneTrader
Explore structured lessons and practical guides to build your market knowledge.
Need a laugh after all that money talk?
Paisa LOL: India's funniest finance page, with memes, comics, jokes and long funny stories.