A high salary does not automatically create wealth. Two people can earn the same amount of money every month and still end up in completely different financial positions after ten or twenty years. One may gradually build investments, reduce debt and increase net worth, while the other may see most of their income disappear into EMIs, lifestyle expenses and consumer purchases. The difference often comes down to one fundamental concept in personal finance: understanding the difference between assets and liabilities.
The words sound simple, but their impact on your financial life is much deeper than their definitions suggest. An asset represents something of economic value that you own, while a liability represents an obligation that you owe. The important question, however, is not simply what belongs in each category. What really matters is how those assets and liabilities affect your cash flow, purchasing power and net worth over time.
Once you start looking at your finances through this framework, many everyday decisions become easier to understand. A car purchase is no longer just a question of whether you can afford the EMI. A home is no longer simply a place to live. A credit card is no longer just a convenient payment method. A salary increase is no longer just extra money to spend. Each decision becomes part of a much larger financial equation.
What Is an Asset?
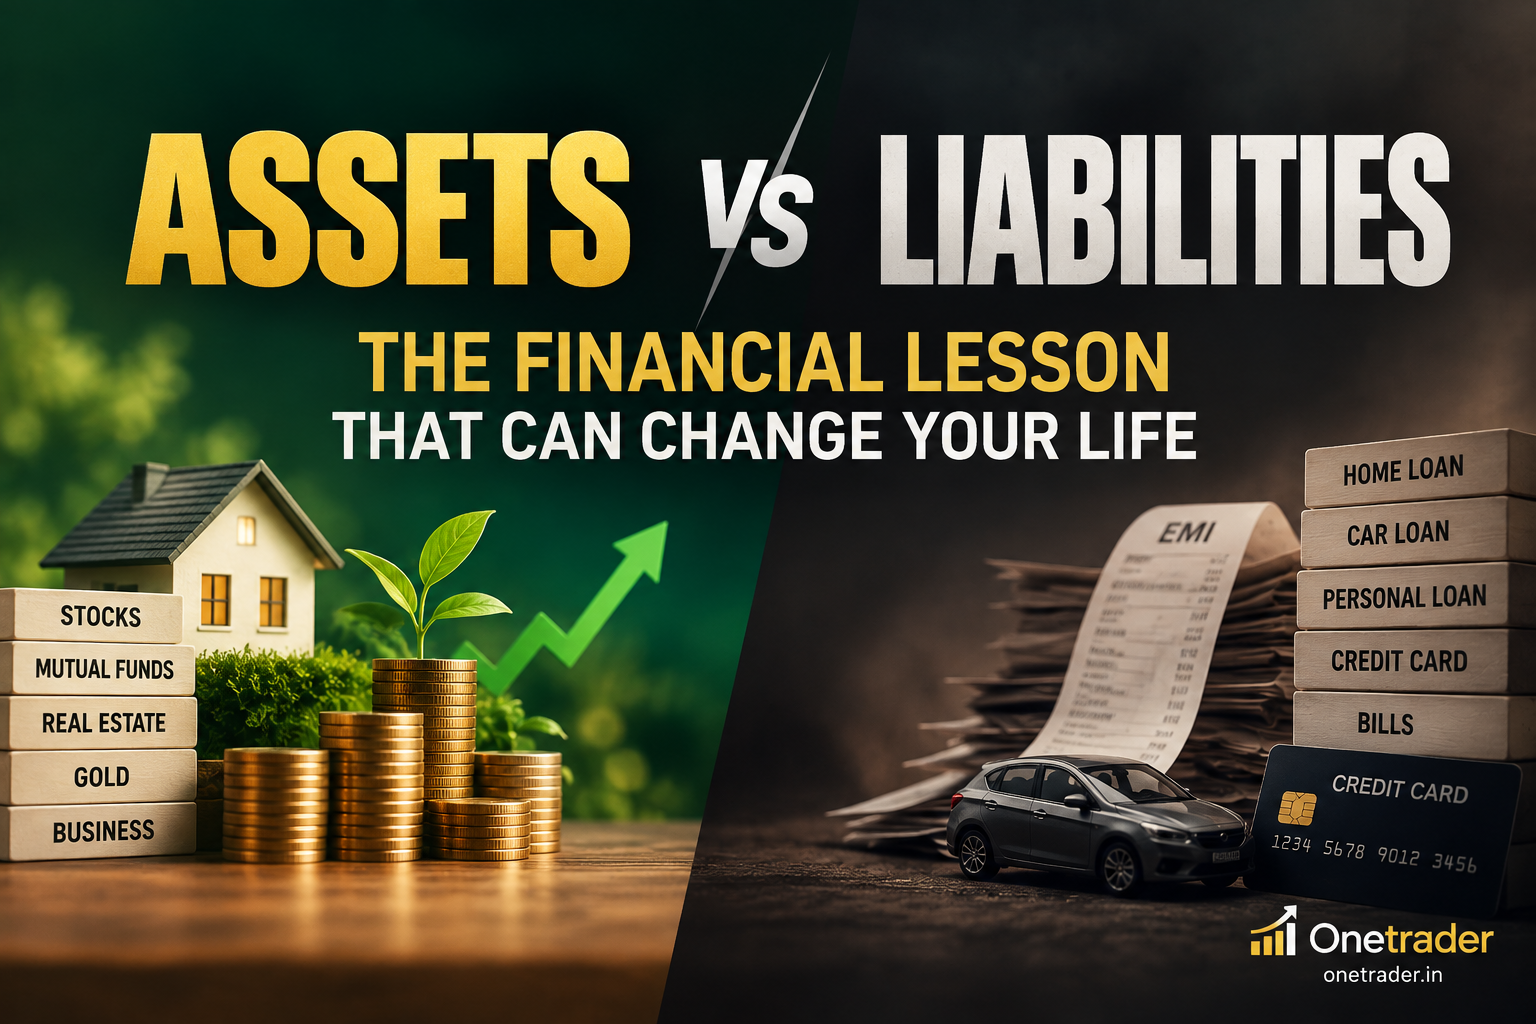
An asset is something that has economic value and contributes to what you own. In personal finance, assets can include cash, fixed deposits, stocks, bonds, mutual funds, ETFs, gold, real estate and ownership in a business. However, simply owning something valuable does not automatically make it a productive wealth-building asset.
Also Read: NPS for NRIs: Who Can Invest, Tax Benefits and Withdrawal Rules
The quality and economic characteristics of an asset matter. A diversified investment portfolio, for example, can potentially appreciate over time and may generate dividends or other distributions. A rental property can potentially generate income while also changing in value. A business can produce profits that are reinvested for future growth. These assets have the potential to contribute to your financial position rather than simply consume money.
This distinction is important because wealth creation is not about collecting expensive things. It is about gradually increasing your ownership of assets that can preserve or potentially increase your purchasing power over time. When a growing portion of your income is converted into productive assets, you begin building a financial base that can work alongside your salary or business income.
What Is a Liability?
A liability is a financial obligation that you owe. Home loans, car loans, personal loans and outstanding credit card balances are common examples. When you take on debt, you are effectively committing a portion of your future income to repay money that you have already used.
Debt itself is not necessarily a financial mistake. Borrowing can sometimes help you acquire an asset or fund something that has the potential to create future economic value. A business may borrow to expand its operations, or a person may borrow for education that improves their future earning potential. But these outcomes are not guaranteed, which means the cost and risk of borrowing still need to be evaluated carefully.
Also Read: How Inflation Destroys Your Wealth & How to Beat It | Complete Beginner Guide – Onetrader
The real danger comes when debt becomes a permanent way of financing consumption. If you repeatedly borrow to purchase things that lose value while continuing to generate no income, your future salary becomes increasingly committed to paying for your past spending. This can create the appearance of a comfortable lifestyle while quietly weakening your financial position.
Your Income Is Not Your Wealth
One of the biggest mistakes people make is confusing income with wealth. Income is what you earn. Wealth is what you accumulate after considering what you own and what you owe.
Imagine someone earning ₹2 lakh every month. On the surface, that looks like a strong income. But suppose that person has a large car loan, a personal loan, substantial credit card spending and expensive lifestyle commitments. A significant part of their future income is already committed before the next salary arrives.
Now consider another person earning ₹1.2 lakh per month who has controlled expenses, limited high-cost debt and consistently invests a portion of their income. The second person may earn substantially less, but their financial position can strengthen steadily because they are converting part of their income into assets.
Also Read: The Power of Compounding: Why Time Is More Valuable Than Money | Onetrader Guide
This is why salary alone is a poor measure of financial progress. A more useful measure is net worth, which is calculated by subtracting total liabilities from total assets. If you own ₹30 lakh worth of assets and owe ₹10 lakh, your net worth is approximately ₹20 lakh. As your investments grow and your outstanding debt declines, your net worth can increase even if your salary does not change dramatically.
Why Assets Matter More Over Time
The importance of assets becomes much clearer when you consider the effect of time. Your salary generally requires continued work. If you stop working, the salary usually stops as well. Productive assets are different because they can potentially continue generating returns without requiring you to exchange another hour of your time for that return.
This is one of the foundations of long-term wealth creation. You work for income, use part of that income to acquire assets, and then allow those assets to potentially grow. Over many years, the combination of additional contributions and compounding can become much more significant than the original amounts invested.
Suppose someone invests ₹20,000 every month for several years instead of allowing the entire amount to disappear into lifestyle expenses. The immediate difference may not look dramatic. But as the investment portfolio grows, the returns generated by the portfolio can themselves begin producing additional returns. Eventually, the investor is no longer relying entirely on their salary to increase their financial resources.
Also Read: Why You Should Pay Yourself First | Smart Money Habit Explained – Onetrader
That is the transition from simply earning money to building wealth.
Why Lifestyle Inflation Can Destroy That Progress
One of the biggest obstacles to building assets is lifestyle inflation. When income rises, people naturally want to improve their standard of living. There is nothing inherently wrong with that. The problem occurs when every increase in income is immediately converted into permanent increases in expenses.
Imagine someone earning ₹1 lakh per month who receives a significant salary increase. Instead of investing a portion of the additional income, they upgrade their car, move into a more expensive apartment, increase discretionary spending and take on new EMIs. Their salary has increased, but their financial flexibility may barely improve.
This creates a cycle in which higher income leads to higher expenses, higher expenses require higher income, and higher income again leads to higher expenses. The person may look increasingly successful from the outside while remaining heavily dependent on their monthly salary.
Also Read: The One Rule Money Never Breaks: Wealth Grows When Your Sources Grow
A healthier approach is to allow your lifestyle to improve while simultaneously increasing your asset base. Every salary increase does not need to become an immediate lifestyle upgrade. Even directing a portion of additional income toward investments can create a significant difference over a long period.
Is Your Home an Asset or a Liability?
A primary residence is one of the best examples of why financial concepts should not be reduced to simple labels. A house has economic value and is therefore an asset on a balance sheet. At the same time, the mortgage used to purchase it is a liability, and owning the property also creates ongoing costs such as maintenance, taxes, insurance and repairs.
The financial outcome depends on the complete picture. If you purchase a ₹1 crore property with a substantial home loan, the property may be worth ₹1 crore, but you do not necessarily own ₹1 crore of equity. Your actual equity depends on the outstanding loan balance. You also need to consider the interest paid over the life of the mortgage and the opportunity cost of the capital used for the purchase.
A property that generates rental income has a different cash-flow profile from a property occupied entirely by its owner. Even then, rental income should be evaluated against financing costs, maintenance, taxes, vacancies and other expenses. Property appreciation is also uncertain and depends on location, demand, economic conditions and the period over which the property is held.
Also Read: The 50-30-20 Rule Explained: Smart Budgeting Made Easy (Day 4 – Money Mastery by OneTrader)
The lesson is simple: don’t judge a financial decision by the label attached to it. Look at the economics behind it.
What About a Car?
Cars provide real utility, but they are usually not the same kind of wealth-building asset as a productive investment. A vehicle generally depreciates with age and usage, while simultaneously creating recurring costs such as fuel, insurance, maintenance and repairs.
Consider someone buying a ₹12 lakh car using a loan. The actual financial commitment is not simply ₹12 lakh. The buyer may also pay interest on the loan, insurance premiums, fuel expenses, maintenance costs and other ownership expenses. Meanwhile, the resale value of the vehicle will generally decline over time.
That doesn’t mean buying a car is wrong. A car may be necessary for work, family responsibilities or convenience. The important question is whether the purchase fits comfortably within your broader financial plan.
Also Read: How to Track Every Rupee You Spend (Day 3 – Money Mastery by OneTrader)
This is why looking only at the EMI can be misleading. A ₹20,000 monthly EMI may appear affordable, but the total cost of owning the vehicle can be substantially higher once every recurring expense is included.
Debt Can Either Support or Weaken Your Financial Position
The phrase “good debt” and “bad debt” is often used in personal finance, but the reality is more nuanced. Debt becomes more financially useful when it helps fund something that has a reasonable possibility of generating future economic value. Even then, the outcome is uncertain.
A business loan can help a profitable business expand, but the business can also fail. An education loan can help someone improve their qualifications, but higher earnings are not guaranteed. A mortgage can help someone acquire property, but property prices can move in either direction.
Consumption debt presents a different challenge because the financial obligation can remain long after the benefit of the purchase has disappeared. This is particularly important with high-interest revolving debt. If a credit card balance is carried forward, interest can accumulate rapidly, making a relatively small original purchase significantly more expensive.
Also Read: The Psychology of Spending: How Emotions Control Your Wallet (Day 2 – Money Mastery by OneTrader)
The most useful question is therefore not whether debt is good or bad in isolation. Ask what the debt is financing, what it costs, how it affects your monthly cash flow and whether you can comfortably service it without sacrificing your long-term financial goals.
The Connection Between Assets, Liabilities and Financial Freedom
Financial freedom is not simply about earning a high salary. It is about creating enough financial strength that your life is not completely dependent on your next paycheck.
Imagine two people with identical salaries. One has substantial investments, manageable debt and a healthy emergency fund. The other has large EMIs, little savings and significant consumer debt. If both suddenly experience a disruption in income, their situations will be very different.
The first person has financial reserves and assets that can provide a degree of flexibility. The second person may immediately face pressure because their financial commitments continue even when their income is interrupted.
Also Read: What is Financial Freedom? A Deep Guide to True Wealth (Day 1 – Money Mastery by Onetrader)
This is why building assets and controlling liabilities is ultimately about creating financial optionality. The more financial resources you accumulate and the fewer unnecessary obligations you carry, the more choices you may have later in life.
How to Improve Your Financial Position
You don’t need to make extreme changes to begin improving the relationship between your assets and liabilities. The process usually starts with understanding where your money is going.
Track your major assets, outstanding loans, monthly repayments and regular investments. Calculate your approximate net worth and review how it changes over time. When your income increases, consider directing part of the increase toward investments rather than automatically increasing your fixed expenses.
If you have expensive debt, reducing that obligation can improve your financial position by lowering future interest costs. At the same time, building an emergency fund can prevent unexpected expenses from forcing you to take on new high-cost debt.
Also Read: 6 Biggest Time Wasters That Stop You from Building Wealth
The objective is not to eliminate every liability or avoid spending money. The objective is to make sure that your financial structure becomes stronger over time.
The Wealth-Building Formula
There is a simple way to think about the entire process:
Earn → Save → Invest → Build Assets → Compound → Repeat
Your job or business generates income. Saving creates the surplus required for investing. Investments create ownership of financial assets. Time allows those assets to potentially compound. As the asset base grows, your dependence on earned income can gradually decrease.
Also Read: 📲 6 Must-Have Govt Apps in India – Detailed Analysis
This is why the earlier concepts in this series are connected. Paying yourself first creates the habit of saving. Understanding inflation shows why simply holding cash may not be enough for long-term goals. Understanding compounding explains how invested capital can grow. Assets and liabilities show where your money is actually going.
Together, these concepts form the foundation of personal finance.
The Question You Should Ask Before a Major Purchase
Before making an expensive financial decision, don’t ask only whether you can afford the monthly payment.
Ask what the decision will do to your financial position five or ten years from now.
Will it increase your assets? Will it create a manageable obligation? Will it reduce the amount you can invest every month? What is the total cost, including interest and maintenance? Most importantly, will the purchase still make sense if your income temporarily falls?
These questions force you to look beyond today’s lifestyle and consider tomorrow’s financial position.
Final Thoughts
Building wealth is not simply about earning more money. It is about what you do with the money after you earn it.
A growing income provides an opportunity, but that opportunity can disappear if every increase in earnings is converted into higher consumption and larger financial obligations. On the other hand, consistently directing a portion of your income toward productive assets can create a financial foundation that becomes increasingly powerful with time.
The goal isn’t to avoid every liability or live without enjoying your money. The goal is to create a balance in which your lifestyle improves without preventing your assets from growing.
Ultimately, financial progress can be viewed through a very simple question: Are you gradually increasing what you own while keeping control of what you owe?
If the answer continues to move in the right direction over many years, your financial position can become stronger even without extraordinary income or complicated investment strategies.
Don’t just work for money. Use a portion of what you earn to build assets that can work alongside you.
Financial Disclaimer: This article is intended for educational and informational purposes only and should not be considered investment, financial, tax, or legal advice. Investment and borrowing decisions involve risk and should be made after considering your individual financial situation, objectives, time horizon and risk tolerance.