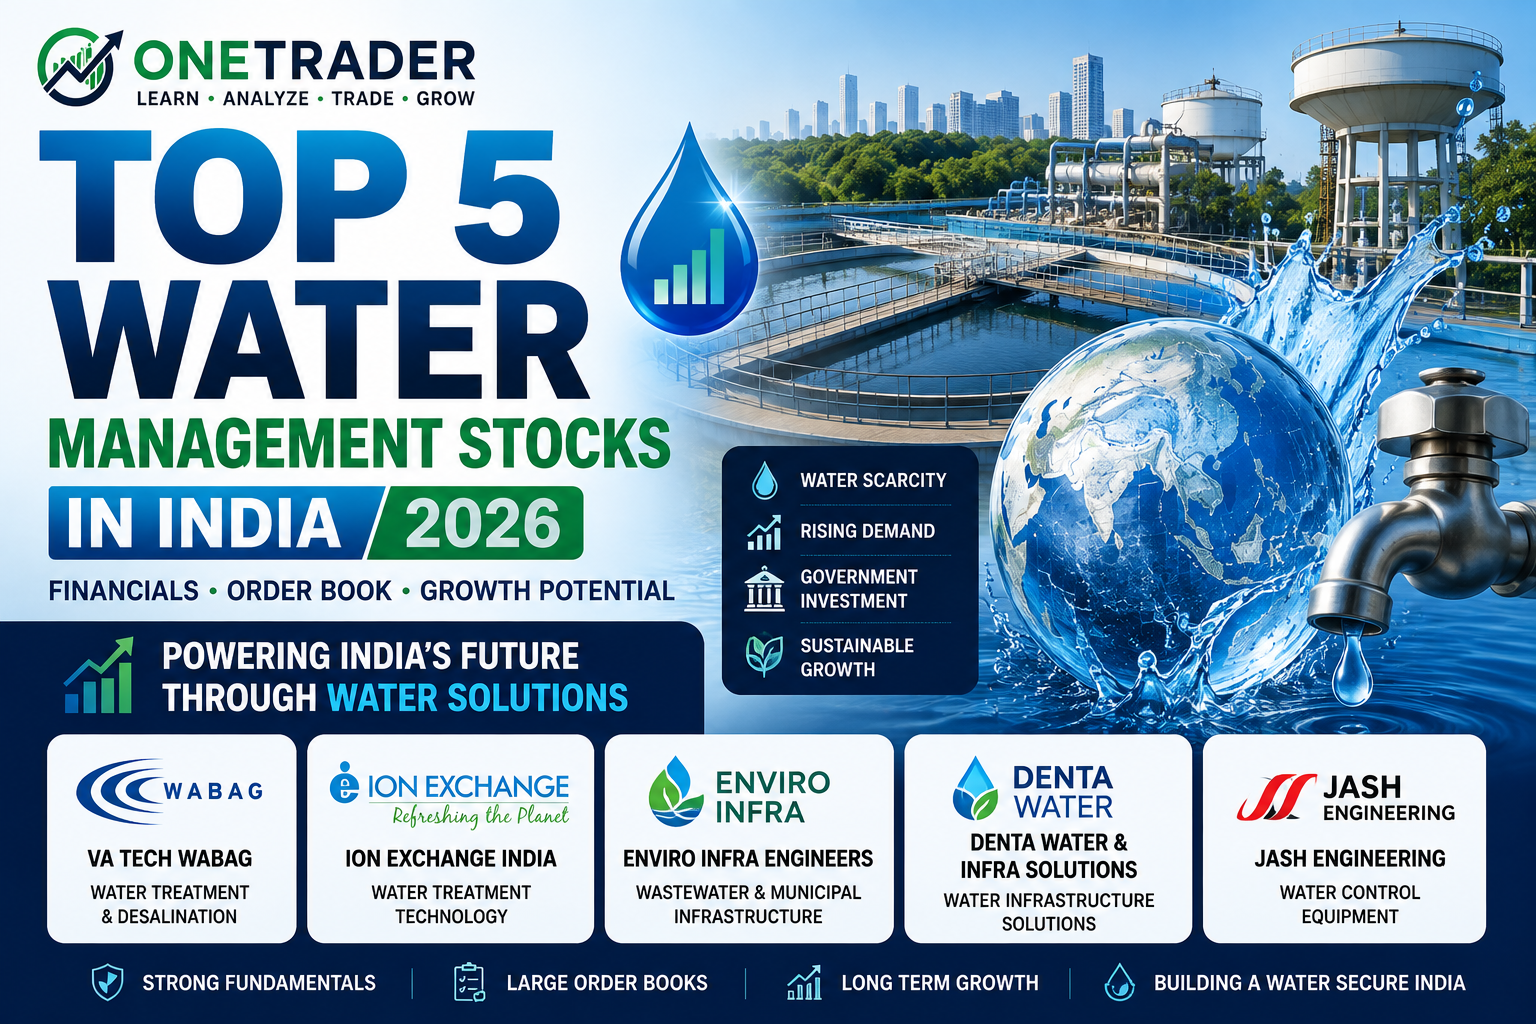
India’s water-management opportunity is moving beyond basic water supply. Rising urbanisation, industrialisation, wastewater generation and increasing water stress are creating demand for treatment plants, recycling, desalination, sewage infrastructure, pumps, specialised equipment and smart water systems. Government programmes are adding another layer of demand. Jal Jeevan Mission 2.0 has been extended to December 2028 with a total outlay of ₹8.69 lakh crore, while urban programmes such as AMRUT 2.0 continue to support water-supply and sewerage infrastructure. This makes water management a potentially important long-duration infrastructure theme for the 2030s.
However, investors should understand that these five companies have very different business models. Some are technology companies, some are EPC players and others manufacture specialised equipment. Therefore, comparing them only on P/E or revenue growth can give a misleading picture.
Also Read: Water: The Hidden Infrastructure of the Future
1. VA Tech Wabag – The Strongest Pure-Play Water Opportunity
VA Tech Wabag is my first company to study in the Indian water-management universe because water treatment is its core business rather than a small division of a diversified industrial company. Wabag operates across drinking-water treatment, wastewater treatment, desalination and related water infrastructure, with a significant international presence.
Also Read: India’s Power & Renewable Energy Sector: Growth, Demand, Future Scope and Key Stocks
FY26 was particularly strong. Consolidated total income reached ₹4,038.5 crore, up 21% year on year, while PAT increased 26% to ₹370.5 crore. More importantly, Wabag ended FY26 with an order book exceeding ₹17,200 crore including framework contracts. The company also reported a net cash position of ₹833.7 crore and maintained its sixth consecutive year of net-cash-positive status.
The order book is the most important part of the investment thesis. At more than ₹17,200 crore, it is several times FY26 revenue, providing substantial medium-term revenue visibility. Of course, an order book is not the same as revenue or cash, so execution and collection remain critical.
Wabag’s international exposure is another advantage. Desalination and wastewater treatment requirements are particularly strong in water-stressed regions such as the Middle East. The company also continued winning international projects in 2026, including a major Vienna water-works order and new wastewater and desalination projects.
The biggest risk is valuation. A high-quality pure-play business can attract a premium, and investors should avoid assuming that excellent business growth automatically means excellent future stock returns.
Also Read: AI and Power Demand: Could Utilities Become the Next AI Winners?
Onetrader view: Among Indian listed companies, Wabag has perhaps the clearest direct exposure to the long-term global water-treatment opportunity.
Also Read: Electronics Mart India: Can the Company Behind Bajaj Electronics Become a Powerhouse?
2. Ion Exchange India – Water Technology With Multiple Revenue Streams
Ion Exchange India is a different type of water company. Its business combines water-treatment engineering, purification technology, ion-exchange resins, chemicals and related environmental solutions. This gives it exposure to both infrastructure and recurring industrial requirements.
Its industrial exposure is particularly interesting because India’s manufacturing expansion will increase demand for reliable water treatment. Pharmaceutical companies, chemicals, food processing, power generation and other industries require increasingly sophisticated water systems.
Also Read: AI and Data Centres: Stocks That Could Benefit From the Infrastructure Boom
FY26, however, showed why investors need to look beyond the long-term story. Standalone revenue from operations increased to ₹2,678.9 crore from ₹2,540.1 crore, but standalone PAT fell to ₹138.4 crore from ₹214.5 crore. The FY26 results also included a ₹14.54 crore adjustment associated with the labour-code changes.
The latest quarterly picture also requires caution. Q4 FY26 revenue was ₹863.3 crore, up only 3.4% year on year, while operating profit declined sharply.
This doesn’t destroy the long-term thesis, but it means the company needs a recovery in margins and earnings to justify stronger growth expectations.
The attractive part is the technology. Water treatment is becoming increasingly sophisticated, and companies with expertise in membranes, resins, purification, recycling and industrial treatment can potentially benefit as industries move toward greater water efficiency.
Also Read: AI Adoption Is Spreading: Which Industries Could Benefit Most?
Onetrader view: Strong technology-oriented water business with diversified exposure, but FY26 earnings weakness means margin recovery should be watched closely.
Also Read: SK Hynix: The Silicon Engine Powering the Global AI Infrastructure Wave
3. Enviro Infra Engineers – Wastewater Could Be the Big Opportunity
Enviro Infra Engineers is one of the more interesting growth companies in this theme because it is positioned strongly toward municipal water and wastewater infrastructure.
The important point is that India’s future water problem isn’t simply about finding more drinking water. Cities also need to collect sewage, treat wastewater and increasingly reuse it. This could make wastewater treatment one of the biggest sub-themes within India’s water economy.
Also Read: Indian Defence Stocks in 2026: Growth Opportunity or Valuation Risk?
Enviro Infra’s FY26 revenue was approximately ₹1,145.6 crore, while PAT was around ₹188.4 crore. The more interesting number was its order book, which reached approximately ₹6,813.6 crore.
That creates substantial future revenue visibility relative to the current revenue base.
But investors should not ignore execution risk. In EPC businesses, a large order book can look impressive while working capital and cash conversion remain challenging. The company therefore needs to demonstrate that order-book growth can translate into revenue, profitability and operating cash flow.
The latest Q4 FY26 quarter showed revenue of ₹427.3 crore, up 8.75% year on year, although operating profit declined 19.9%.
Also Read: Renewable Energy & Clean Tech Stocks in India: Complete List
That margin pressure is worth monitoring.
Onetrader view: One of the more interesting growth candidates in wastewater infrastructure, but cash flow and margins are more important than simply chasing its large order book.
Also Read: How Is Crude Oil Formed? The 300-Million-Year Process Explained
4. Denta Water & Infra Solutions – Small-Cap Growth With Higher Risk
Denta Water offers a more aggressive way to participate in India’s water-infrastructure expansion. The company is involved in water-related infrastructure projects including water supply and treatment-related work.
Also Read: Is India’s Real Estate Boom Back? What Investors Need to Know
Its FY26 revenue was approximately ₹250.4 crore and PAT around ₹60.9 crore, while the order book stood at approximately ₹727.8 crore.
The size of the order book compared with annual revenue is what makes Denta interesting. If the company executes efficiently, the order pipeline can support substantial growth over the next several years.
But this is also where the risk increases.
A small company executing large infrastructure projects can experience significant working-capital requirements, project concentration and quarterly volatility. The latest Q4 FY26 numbers showed revenue of ₹55.3 crore, up only 2.1% year on year, while operating profit and PAT declined materially.
Also Read: Water: The Hidden Infrastructure of the Future
Therefore, Denta should not be viewed simply as a “high-growth water stock”. Investors need to see whether the company can consistently convert its order book into revenue and cash.
Onetrader view: Higher-risk, higher-growth candidate. Attractive if execution remains strong, but it requires much closer monitoring than Wabag.
Also Read: The Little Book of Common Sense Investing – Why Index Funds Win | Onetrader
5. Jash Engineering – The Equipment Play
Jash Engineering gives investors a different exposure to the water ecosystem. Instead of primarily building complete water-treatment projects, the company manufactures specialised equipment used in water and wastewater infrastructure.
Also Read: Infrastructure Investment Trusts (InvITs) in India – Complete Beginner Guide | Onetrader
This is an important business model because water infrastructure ultimately requires physical equipment such as gates, screens and flow-control systems.
Jash reported FY26 revenue of approximately ₹736 crore, broadly flat year on year. EBITDA declined from ₹138 crore to ₹123 crore, while PAT fell from ₹87 crore to ₹76 crore.
So FY26 wasn’t particularly strong financially.
However, the company continues to benefit from the long-term requirement for water-control equipment, and its business is less dependent on simply winning large Indian municipal EPC contracts.
Also Read: Top Space-Tech Stocks in India – A Hidden Multibagger Opportunity (2025-2045)
The downside is that international exposure brings additional risks. Export conditions, geopolitical developments, tariffs and subsidiary performance can affect results.
Onetrader view: A more specialised “picks-and-shovels” water business. FY26 weakness means investors should look for a recovery in sales and margins rather than relying purely on the sector’s long-term story.
Also Read: Herd Mentality in Stock Market – Why Following the Crowd Leads to Losses
Final Ranking From an Onetrader Perspective
If I were building a research watchlist rather than giving a buy recommendation, my ranking would be:
Also Read: Green Energy & EV Ecosystem – The Future of Power (2025–2035)
1. VA Tech Wabag – Best pure-play water business
2. Ion Exchange India – Best technology/diversified water exposure
3. Enviro Infra Engineers – Strong wastewater growth opportunity
4. Denta Water – Higher-growth small-cap opportunity
Also Read: Drone & Anti-Drone – The Futuristic Industry (2025 – 2035)
5. Jash Engineering – Specialised water-equipment play
The ranking does not mean No. 1 will necessarily generate the highest stock return. It represents the quality and attractiveness of the underlying water-business opportunity based on current information.
The biggest theme I would watch over the next decade is wastewater recycling. India will increasingly need to move from a “use once and discharge” model toward a circular system where wastewater is treated and reused. That creates demand for treatment plants, membranes, pumps, monitoring systems and specialised equipment.
The second major opportunity is industrial water treatment. Semiconductor manufacturing, pharmaceuticals, chemicals, data centres and advanced manufacturing all require reliable and increasingly sophisticated water systems.
Also Read: AI & Cloud – The Complete Future Playbook
The third is desalination and water security, particularly in coastal and water-stressed regions.
For investors, the most important lesson is simple: don’t buy a water stock just because water scarcity is increasing. Examine order-book quality, cash flow, working capital, margins, debt, execution capability and valuation.
Water could become a major infrastructure theme through 2035, but the companies that create the greatest shareholder value will probably be those that combine strong technology, efficient execution, healthy balance sheets and sustainable cash generation.
Onetrader conclusion: If we are building a long-term Water Sector watchlist, Wabag deserves the first place for pure-play exposure, while Ion Exchange, Enviro Infra, Denta and Jash provide different ways to participate in the broader water economy. This is a sector worth tracking for the next decade rather than judging only by the next few quarters.
Also Read: AMD vs NVIDIA: The AI War That Will Define the Next Decade
Disclaimer: This article is for educational purposes only and is not investment advice or a buy/sell recommendation. Financial results, valuations and business conditions can change. Investors should independently verify the latest company filings before making investment decisions.