🟠 Hindustan Copper Ltd – Complete Business Analysis, Moat, Management Strategy & 2025–2035 Outlook
By Onetrader Guide
🧭 Introduction
Hindustan Copper Ltd is India’s only vertically integrated copper ore mining company and a strategic PSU under the Ministry of Mines.
Copper is no longer just an industrial metal.
It is the backbone of:
- Electrification
- Renewable energy
- Electric vehicles
- Power transmission
- Data centres
- Defence & railways
This makes Hindustan Copper a strategic national asset, not just a commodity company.
Also Read: Sai Life Sciences: The Hyderabad Pharma Research Company Building a Global Drug Development Business
Also Read: HBL Engineering Ltd – Business Model, Railway Safety Moat & Long-Term Outlook
🏢 Company Overview
| Parameter | Details |
|---|---|
| Founded | 1967 |
| Ownership | Government of India (~66%) |
| Sector | Mining & Metallurgy |
| Core Product | Copper ore, concentrate, cathodes |
| Operations | Rajasthan, Jharkhand, Madhya Pradesh |
| Nature | Mining + Smelting (integrated) |
HCL is the only PSU in India with copper mining rights and integrated processing capability.
⚙️ Business Model – How HCL Makes Money
HCL operates across the entire copper value chain:
- Exploration & Mining
Copper ore extracted from captive mines - Beneficiation
Ore → copper concentrate - Smelting & Refining
Concentrate → copper cathodes - Sale to End Users
Power, cables, EVs, transformers, defence, railways
This integration reduces raw-material risk compared to pure smelters.
Also Read: Tonbo Imaging: The Indian Defence Technology Company Building Eyes for Modern Warfare
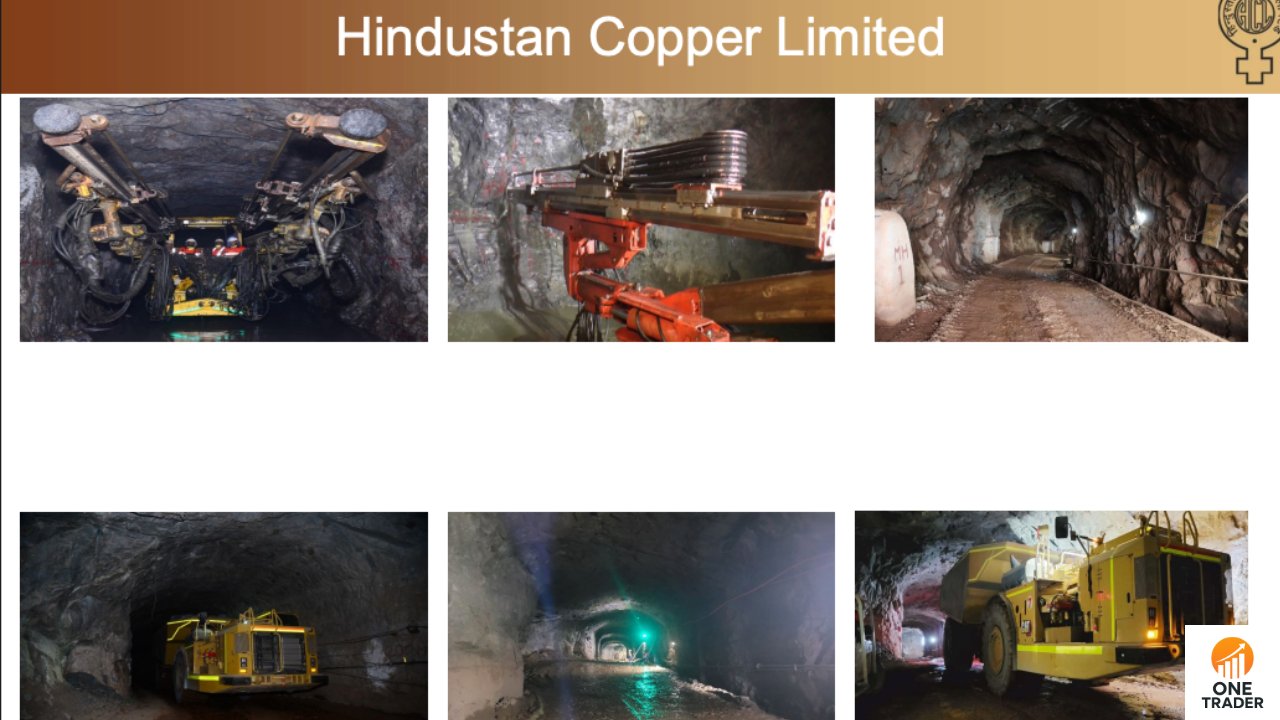
🪨 Mining Operations (Core Asset)
Major Mining Locations:
- Khetri Copper Complex (Rajasthan)
- Malanjkhand Copper Project (Madhya Pradesh)
- Indian Copper Complex (Jharkhand)
These mines give HCL strategic domestic supply, reducing import dependence.
🔌 End-Use Demand Drivers (Why Copper Is Strategic)
Copper demand is exploding due to:
- EVs (4× copper vs ICE vehicles)
- Renewable energy (solar, wind, storage)
- Power transmission & grid expansion
- Data centres & digital infrastructure
- Defence & railways
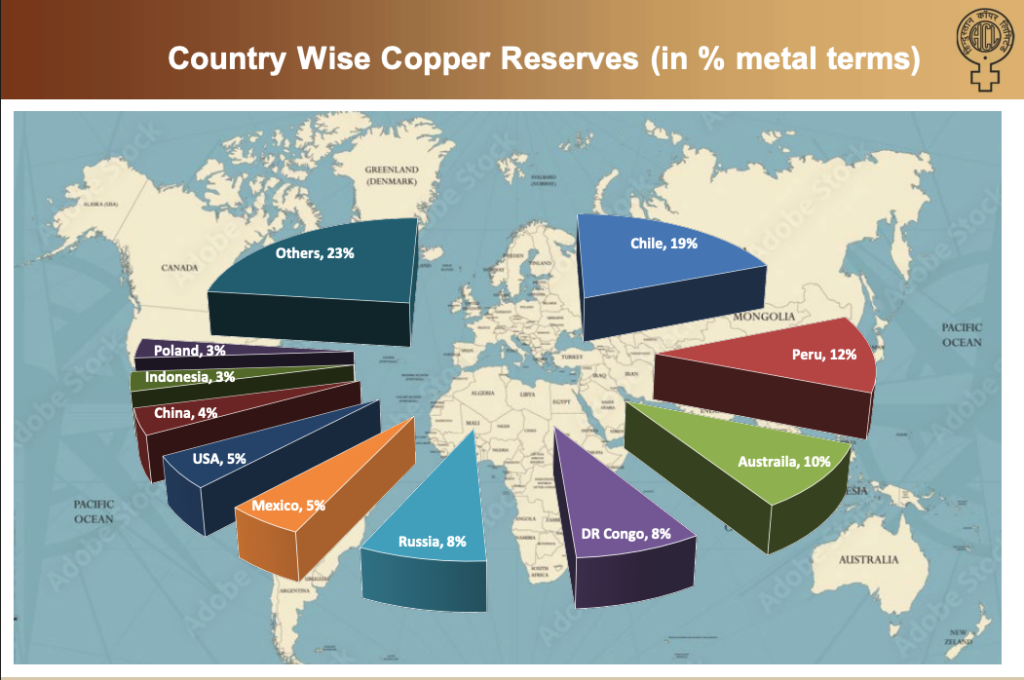
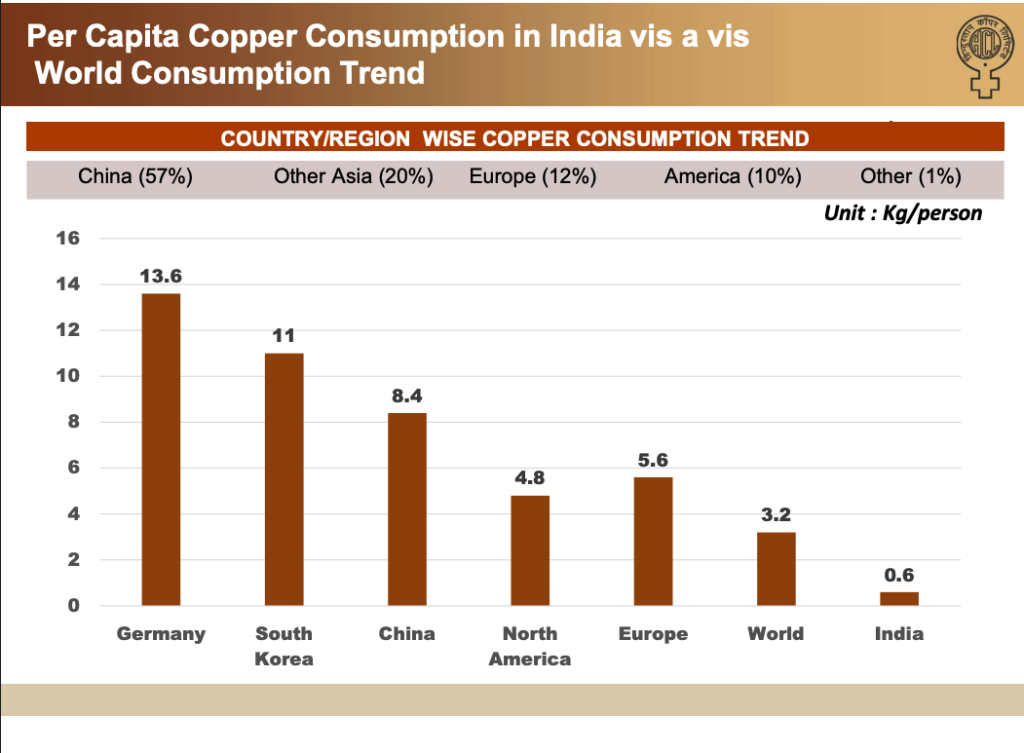
India currently imports ~90% of copper requirement → HCL’s role becomes critical.
🧱 Moat – Why Hindustan Copper Is Unique
⭐ 1️⃣ Monopoly in Copper Mining (India)
HCL is the only domestic copper miner.
No private player has mining rights at scale.
Also Read: Lupin: How India’s Pharma Giant Is Moving Beyond Generic Medicines
⭐ 2️⃣ Strategic PSU Status
Government support for:
- Mining leases
- Expansion approvals
- Strategic minerals
Copper is treated as a critical mineral.
⭐ 3️⃣ Vertical Integration
Mining → refining → cathodes
This lowers cost volatility compared to import-dependent smelters.
⭐ 4️⃣ High Entry Barriers
Copper mining requires:
Also Read: Blue Star: The Indian AC Maker Building a Bigger Business Beyond Home Cooling

- Geological expertise
- Environmental approvals
- Decades of capex
- Long gestation
New entrants are almost impossible.
⭐ 5️⃣ Long-Life Assets
Copper mines can operate for 30–50 years.
🧑💼 Management Commentary & Strategic Thinking (IMPORTANT)
You were right earlier — so this section is mandatory now 👇
🎯 Management Vision (Onetrader Interpretation)
HCL management has clearly stated its goal:
Also Read: Jio Platforms: From India’s Biggest Telecom Network to a Digital Technology Powerhouse
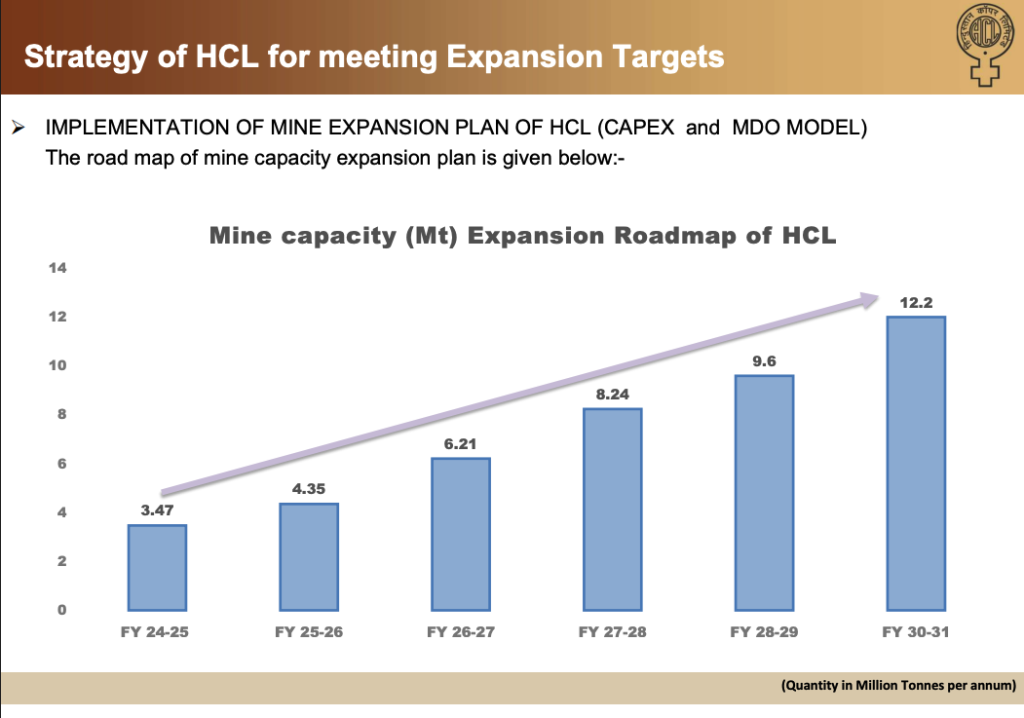
To triple ore production over the next decade.
This is not short-term optimism — it is backed by:
- Mine expansion plans
- New shafts
- Underground mining tech
- Brownfield expansions
🔍 What Management Is Focusing On
1️⃣ Volume Expansion Over Price Speculation
Management is not betting on copper prices.
They are betting on:
Also Read: Piramal Pharma: The Global Drug Manufacturing Business Building Its Next Growth Engine
- Higher domestic production
- Better mine utilization
- Lower unit costs
2️⃣ Reducing Import Dependence
India’s copper deficit is a policy concern.
HCL is positioned as:
- Strategic supplier
- Import substitution enabler
This aligns with Make in India.
3️⃣ Modernising Legacy Assets
HCL is upgrading:
- Old shafts
- Mining equipment
- Beneficiation technology
Goal: improve recovery & margins.
4️⃣ Disciplined Capex
Capex is:
- Phased
- Project-linked
- Government approved
Avoids reckless expansion.
🧠 Onetrader Take on Management
✔ PSU-style conservative
✔ Long-term planners
✔ No hype-driven commentary
✔ Focus on volumes & execution
Also Read: PC Jeweller: From Debt Crisis to a Debt-Free Jewellery Retailer — Can Its Next Expansion Deliver?
This is execution-first management, not market-facing.

📊 Financial Characteristics (Conceptual)
HCL shows:
- Revenue sensitivity to copper prices
- Operating leverage when prices rise
- PSU-level margins (moderate)
- Capex-heavy but long-life assets
- Improving ROCE with scale
This is cyclical + strategic, not FMCG-like.
🚀 Growth Drivers (2025–2035)
🚀 1️⃣ Copper Demand Supercycle
EVs, renewables, grid expansion = structural demand.
Also Read: Vodafone Idea: Can India’s Telecom Challenger Turn Its 5G Expansion Into a Business Comeback?
🚀 2️⃣ Capacity Expansion
Planned ore production increase → revenue growth.
🚀 3️⃣ Import Substitution Policy
Government backing for domestic minerals.
🚀 4️⃣ Defence & Railways
Strategic copper supply to national projects.
🚀 5️⃣ Global China+1 Theme
Global supply chain diversification boosts copper value.
⚠️ Risks You Must Understand
⚠ Commodity price volatility
⚠ PSU execution delays
⚠ Environmental & land approvals
⚠ Capex overruns
⚠ Operational risks (mining accidents)
These are structural mining risks, not company-specific red flags.
🔍 Hindustan Copper vs Other Copper Players
| Company | Nature |
|---|---|
| Hindustan Copper | Mining + refining (domestic monopoly) |
| Vedanta | Smelting, no mining |
| Hindalco | Aluminium-focused, copper refining |
| Global miners | Large-scale but not Indian |
HCL’s mining monopoly is the key differentiator.
🎯 Onetrader Final Verdict
Hindustan Copper is not a trader’s stock.
It is a strategic commodity + national asset play.
Best suited for:
✔ Long-term investors
✔ Those bullish on electrification & EVs
✔ Investors understanding commodity cycles
✔ Portfolio exposure to critical minerals
Onetrader Rating: ⭐⭐⭐⭐☆ (4/5)
Category: Strategic Commodity PSU
Theme: Copper Supercycle + Energy Transition
Keep learning with OneTrader
Explore structured lessons and practical guides to build your market knowledge.

Need a laugh after all that money talk?
Paisa LOL: India's funniest finance page, with memes, comics, jokes and long funny stories.