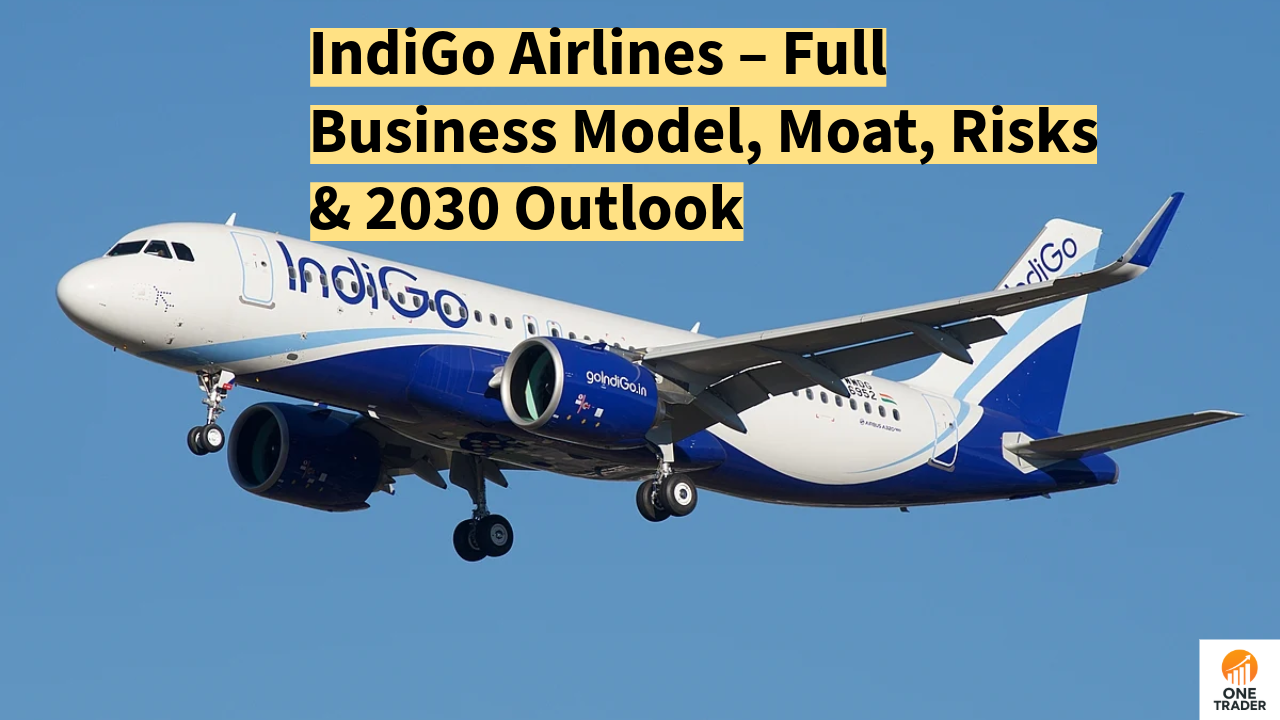
✈️ InterGlobe Aviation (IndiGo Airlines) – Full Business Analysis, Moat, Risks & 2025–2030 Long-Term Outlook
By Onetrader Guide
🧭 Introduction
InterGlobe Aviation Ltd, operating India’s largest airline IndiGo, is not just an airline — it is a logistics, mobility, and aviation powerhouse controlling over 60% domestic market share.
In an industry known for bankruptcies and losses, IndiGo stands out because it cracked the low-cost carrier model, turned scale into power, and built an unbeatable operational advantage.
This is a complete, in-depth business analysis covering:
- Business model
- Revenue streams
- Fleet strategy
- Cost leadership
- Moat
- Management philosophy
- Financials
- Risks
- Future outlook
Let’s begin.
Also Read: Sai Life Sciences: The Hyderabad Pharma Research Company Building a Global Drug Development Business
Also Read: ICICI Bank — Complete Business Model, Moat, Financials & Long-Term Outlook
🛫 1. Company Overview
| Parameter | Details |
|---|---|
| Company | InterGlobe Aviation Ltd (IndiGo) |
| Founded | 2006 |
| Headquarters | Gurugram, India |
| Founders | Rahul Bhatia & Rakesh Gangwal |
| Fleet Size | 350+ aircraft |
| Market Share | 60%+ in domestic aviation |
| Employees | 35,000+ |
| Business Model | Low-cost carrier (LCC) |
IndiGo is now the world’s 6th largest airline by market capitalization and one of the most consistently profitable LCCs globally.
🛫 2. IndiGo’s Business Model – How It Really Works
IndiGo operates on the Low-Cost Carrier (LCC) model designed around efficiency + scale + simplicity.
The model is built on four pillars:
Also Read: Tonbo Imaging: The Indian Defence Technology Company Building Eyes for Modern Warfare
🔹 A) Single Aircraft Type – A320 Family
IndiGo uses only Airbus A320/A321 aircraft.
Benefits:
- Lower training cost
- Lower maintenance cost
- Higher operational efficiency
- Easy swapping between flights
This single-type strategy is a huge cost advantage.
🔹 B) Point-to-Point Network Model
Unlike full-service carriers (Air India, Vistara), IndiGo avoids complex hub systems.
Advantages:
- Faster turnaround
- Less dependency on connecting flights
- More frequency on popular routes
- Low delays
🔹 C) High Aircraft Utilization
Airlines make money only when planes are flying.
IndiGo’s aircraft utilization is among the highest in the world.
Also Read: Lupin: How India’s Pharma Giant Is Moving Beyond Generic Medicines
They aim for 12–14 hours of flying per day, which dramatically boosts revenue.
🔹 D) Lease Instead of Buy
IndiGo uses a sale-and-leaseback model:
- Orders aircraft
- Buys at lower negotiated price
- Sells to leasing companies
- Leases back for 8–12 years
This reduces:
- Capex
- Debt burden
- Upfront cost
It is the reason IndiGo maintains a strong balance sheet while expanding aggressively.
Also Read: Blue Star: The Indian AC Maker Building a Bigger Business Beyond Home Cooling
💰 3. Revenue Streams
IndiGo earns revenue from multiple sources — not just ticket sales.
1️⃣ Passenger Revenue (Core Business)
- Domestic passengers
- International passengers
- Highest market share in India
2️⃣ Ancillary Revenue (Very Important)
Includes:
- Seat selection
- Meals onboard
- Excess baggage
- Priority check-in
- Cancellation fees
- Loyalty program co-branded cards
Ancillary revenue contributes ~20%+ of sales — a major strength.
3️⃣ Cargo & Logistics (IndiGo CarGo)
Huge growth post-COVID.
IndiGo is building a fleet of A321 converted freighters.
Also Read: Jio Platforms: From India’s Biggest Telecom Network to a Digital Technology Powerhouse
4️⃣ Sale-and-Leaseback Income
Important source of cash, reduces cost of fleet expansion.
5️⃣ International Operations
IndiGo is expanding aggressively to
- Middle East
- Southeast Asia
- Central Asia
- Europe (via code-share partnerships)
International yields are much higher than domestic.
🧱 4. Moat – Why IndiGo Is Almost Impossible to Replace
IndiGo’s leadership exists because of operational excellence, not discounts.
Also Read: Piramal Pharma: The Global Drug Manufacturing Business Building Its Next Growth Engine
⭐ 1) Market Share Dominance
Controlling 60%+ of the market gives them pricing power.
⭐ 2) Lowest Operating Costs
Cost per available seat kilometer (CASK) is among the lowest globally.
⭐ 3) Strong Brand & On-Time Performance
IndiGo’s brand is built on reliability:
- Highest on-time performance (OTP)
- Fewer cancellations
- Simpler travel experience
This trust = repeat customers.
⭐ 4) Massive Fleet Advantage
IndiGo has 1,000+ aircraft on order — one of the largest airline orders in the world.
No other Indian airline can match this scale.
⭐ 5) Efficient Management
IndiGo’s leadership focuses on:
- Simplicity
- Low cost
- High utilization
- Zero unnecessary features
This is why the airline has avoided the losses typical in aviation.
Also Read: PC Jeweller: From Debt Crisis to a Debt-Free Jewellery Retailer — Can Its Next Expansion Deliver?
⭐ 6) Domestic Duopoly Advantage
Competitors:
- Air India (rebuilding)
- Akasa (new)
- SpiceJet (struggling)
- Vistara (merging into Air India)
IndiGo is the only fully stable airline today.
📊 5. Financial Performance (FY24–FY25)
| Metric | Value |
|---|---|
| Revenue | ₹65,000+ crore |
| Net Profit | ₹7,000+ crore |
| EBITDA Margin | 20%+ |
| Market Share | 60%+ |
| Load Factor | ~85% |
| Cash Reserve | Strong |
Even when fuel prices rise, IndiGo maintains efficiency due to operational discipline.
🧑✈️ 6. Management Philosophy
IndiGo follows “Three E Principles”:
Also Read: Vodafone Idea: Can India’s Telecom Challenger Turn Its 5G Expansion Into a Business Comeback?
✔ Efficiency
Simple processes, low cost, maximum utilization.
✔ Economy
Focus on affordability and profitability.
✔ Experience
Smooth, fast, reliable passenger experience.
Management Commentary
“India is the world’s fastest-growing aviation market, and IndiGo is uniquely positioned to expand in both domestic and international segments.”
— Pieter Elbers, CEO
“Our long-term goal is to become a global-sized Indian aviation company.”
Onetrader Interpretation:
Management wants IndiGo to evolve from a domestic airline to a global aviation brand — similar to Ryanair or Southwest Airlines.
🌍 7. Growth Drivers (2025–2030)
🚀 1) India’s Air Travel Boom
Only 3–4% Indians fly. Massive scope ahead.
🚀 2) International Expansion
Routes to:
- Turkey
- Central Asia
- Middle East
- Singapore
- Bali
- Europe via partnerships
International = higher yields.
🚀 3) Fleet Expansion
1,000+ aircraft orders → multi-decade runway for growth.
🚀 4) Cargo
Freighter fleet + eCommerce boom.
🚀 5) Rising Middle-Class Travel
Tier-2 and Tier-3 airport connectivity exploding under UDAN.
Also Read: Delhivery Business Analysis: How India’s Technology-Driven Logistics Company Makes Money
🚀 6) Code-Share Alliances
Partners:
- Turkish Airlines
- Qatar Airways
- Qantas
More revenue + better reach.
⚠️ 8. Risks
Aviation = a sensitive industry. Risks include:
⚠ ATF (Aviation Fuel) price volatility
⚠ Rupee depreciation (costs in USD)
⚠ Pilot/crew shortages
⚠ Competition from Air India after Tata transformation
⚠ Regulatory pressure on fares
⚠ Aircraft supply issues (Pratt & Whitney engine troubles)
Also Read: VRL Logistics: Inside India’s Road Transport Giant and Its Expanding Logistics Business
However, IndiGo is financially strong to handle industry cycles.
🎯 9. Onetrader Final Verdict
IndiGo is one of India’s strongest long-term consumer + infrastructure + mobility plays.
✔ Zero-nonsense management
✔ Strong cost control
✔ Unbeatable market share
✔ Clear runway for 10+ years of growth
✔ Strong balance sheet
✔ Global expansion story beginning
Onetrader Rating: ⭐⭐⭐⭐⭐ (5/5)
Category: Long-Term Compounder
Theme: Aviation + Consumer Mobility + Global Expansion
Also Read: ITC Farm-to-Food Business Model: Sourcing, Brands and Cash Flow
Keep learning with OneTrader
Explore structured lessons and practical guides to build your market knowledge.
Need a laugh after all that money talk?
Paisa LOL: India's funniest finance page, with memes, comics, jokes and long funny stories.