
Detailed Onetrader analysis of Colgate-Palmolive (India) Ltd — business model, management insights, FY25 financials, GST impact, and a clear 2025–2030 roadmap for investors.
- The great bulk of sales come from oral care: toothpaste, toothbrushes, mouthwash and toothpowder.
- It sells through lakhs of retail outlets, from large supermarkets to village kiranas.
- The brand has been a household habit for generations, and dentists recommend it widely.
Every morning, millions of Indian households reach for the same red-and-white tube. Colgate-Palmolive India sells toothpaste, and because people buy it again and again whatever the economy is doing, the business is among the steadiest in consumer goods.
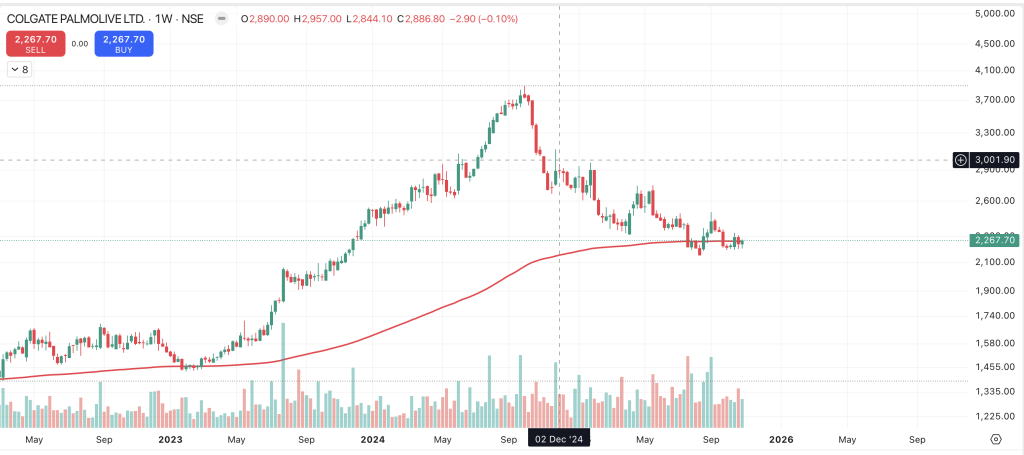
It is the Indian arm of the US company Colgate-Palmolive, headquartered in Mumbai and led by Prabha Narasimhan. It is the largest oral care company in the country, with well over half the toothpaste market by most measures.
What Colgate-Palmolive India Does
The great bulk of sales come from oral care: toothpaste, toothbrushes, mouthwash and toothpowder. Toothpaste is a small, frequent purchase, which is why demand is so consistent. The company is steadily moving customers from basic pastes to premium ones such as Colgate Total, Visible White, Sensitive and PerioGard, which carry higher prices and margins.

Customers and How the Company Makes Money
It sells through lakhs of retail outlets, from large supermarkets to village kiranas. The model rests on frequency, familiarity and trust: a customer who buys a tube several times a year rarely thinks about switching. Higher-priced products raise the average selling price, and the brand’s strength lets the company keep margins healthy while spending moderately on manufacturing and marketing.
Also Read: Apollo Hospitals: How India’s Healthcare Giant Is Building Growth
Why Its Position Is Hard to Copy
The brand has been a household habit for generations, and dentists recommend it widely. Distribution reaches deep into rural India, supported by decades of advertising and education about oral health. Competitors such as Hindustan Unilever, Dabur and Patanjali have gained ground in specific segments, but dislodging a daily habit is hard. Because the company pays regular dividends and needs little capital, it returns a high share of profit to shareholders.
How Management Is Steering the Company
Management’s focus is premiumisation, bringing in more advanced products such as whitening and gum care, along with herbal and natural variants, and strengthening rural reach. It is also expanding e-commerce sales and educating consumers about brushing habits and dental check-ups, since more users and better habits raise the category itself.
Growth Drivers
Per-capita use of toothpaste, mouthwash and electric brushes in India is still low, so there is room to grow as incomes rise. GST changes and lower tax on essentials can help demand. Premium products and rural expansion can lift both volume and price.
Competition and Risks
Natural and herbal brands have taken share in recent years, which pressures the core business. Raw material costs and packaging prices can affect margins. Growth in toothpaste is slow compared with other consumer categories, and a parent company’s decisions on royalty fees can influence profits.
Also Read: Trent: How Westside and Zudio Are Driving Growth
What Investors Should Watch
The mix of premium products, market share against herbal rivals, rural volume growth and the royalty paid to the parent all matter. Colgate India is a steady, cash-generating compounder rather than a fast grower.
Financial Disclaimer: This article is for educational and informational purposes only. It is not investment advice or a recommendation to buy or sell any security. Investors should review company disclosures, financial statements, risks and valuations and consult a qualified financial adviser before making investment decisions.
Keep learning with OneTrader
Explore structured lessons and practical guides to build your market knowledge.

Need a laugh after all that money talk?
Paisa LOL: India's funniest finance page, with memes, comics, jokes and long funny stories.
